Insurance Career Guide
Explore career paths across the insurance industry, build the skills and knowledge employers value, prepare for interviews, and stay informed on the news and trends that can help you grow throughout your career in insurance.
The Top Insurance News, in 5 Minutes.
We select the best insurance newsletters and turn them into a 5-minute audio briefing with the most important news, trends, and insights in insurance. Texted to you every morning.
Try Our Insurance BriefingFree
At a glance
Insurance at a Glance
Insurance employs almost three million people in the United States, and careers in the industry extend far beyond selling policies. Insurance is a collection of connected specialties: underwriters who evaluate and price risk, claims professionals who investigate and settle losses, actuaries who model financial outcomes, brokers who advise clients and place coverage, and professionals working across compliance, reinsurance, catastrophe modeling and insurance technology.
Pay varies considerably by role, experience and professional credentials. The industry also offers career paths for a wide range of strengths, from quantitative analysis and risk assessment to negotiation, client service and regulatory expertise.
There is no insurance degree standing between you and the field. Most insurance jobs ask for a bachelor's degree in no particular subject, and the credentials that matter are earned on the job: state licenses for adjusters and producers, the CPCU for underwriting and broking, and the Society of Actuaries exams for actuarial work. That is what gives insurance career paths their shape, since progression tends to follow the exams and designations you finish while working. It is also why insurance industry trends are worth following from your first year, as AI underwriting and claims automation take on the routine decisions and leave the judgement calls to people.
Key Industry Statistics
2.93M
People employed in US insurance carriers and related activities (September 2026)U.S. Bureau of Labor Statistics
2.1%
Unemployment rate across the insurance sector (September 2026)U.S. Bureau of Labor Statistics
$130,000
Median pay for actuaries, the highest paid core insurance role (May 2025)U.S. Bureau of Labor Statistics
572,600
Insurance sales agent jobs, the industry's largest single occupation (2025)U.S. Bureau of Labor Statistics
Common roles
- Underwriter
- Claims Adjuster
- Actuary
- Insurance Broker
- Risk Manager
- Loss Control Consultant
- Compliance Analyst
- Reinsurance Analyst
Where you can work
- Carriers and insurers
- Brokerages and agencies
- Reinsurers
- Lloyd's and the specialty market
- Insurtech
- Risk management teams in industry
- State regulators and the NAIC
- Consulting and actuarial firms
Core skills
- Risk assessment and judgement
- Data analysis and modelling
- Policy wording and coverage literacy
- Negotiation
- Regulatory awareness
- Clear written reasoning
Key Areas in Insurance
Underwriting
Decide which risks to accept, on what terms, and at what price.
Claims
Investigate what happened, apply the policy to it, and settle what is owed.
Actuarial & Pricing
Model expected losses and set the rates and reserves the business runs on.
Brokerage & Distribution
Represent the buyer, place the risk, and negotiate the terms with carriers.
Risk Management
Reduce the loss before it happens, inside a company rather than an insurer.
Compliance & Regulation
Keep filings, licensing and solvency in line with fifty state regulators.
Insurance Jobs & Salaries
Federal wage data measures occupations rather than seniority, so this is what the government actually records for the jobs in this field, not a promised ladder. Figures are national medians across all industries. Note the direction of travel: the two largest occupations are both projected to shrink this decade while actuarial work grows, which is the clearest statement anyone has made about where automation is landing.
Insurance sales agents
$62,280
Claims adjusters, examiners and investigators
$78,020
Insurance underwriters
$81,370
Actuaries
$130,000
Source: US Bureau of Labor Statistics, Occupational Outlook Handbook, May 2025 wage data, accessed October 2026.
Insurance Career Paths
Insurance is not one ladder, it is four or five parallel ones that occasionally cross. The function you enter shapes almost everything that follows: what you are measured on, which credential you chase, and whether your next move is to a carrier, a broker or out to a corporate risk team. People do move between tracks, most commonly from claims into underwriting, but the first choice matters more here than in most industries.
- Underwriting Assistant or Trainee0 to 2 yearsPrepare submissions, order loss runs and inspections, learn the appetite. You are being taught what the company will and will not write.
- Underwriter2 to 5 yearsHold authority on a book inside set limits. The first time a price and a declination are genuinely yours.
- Senior Underwriter5 to 10 yearsLarger limits, harder accounts, broker relationships you own. You are expected to defend a number to someone who wants a different one.
- Underwriting Manager or Product Head10+ yearsSet appetite and pricing strategy for a line. You now answer for a portfolio rather than a file.
Credential that fits CPCU, the property and casualty profession's main designation, usually taken over two to four years
Years are typical rather than required, and the specialty market moves faster than the standard one.
A Typical Day in Insurance Jobs
Five roles, five quite different days. The pattern that repeats is the same one that defines the industry: a morning of judgement calls on individual files, an afternoon of defending those calls to someone with a different incentive.
Underwriting AssistantEntry-Level · UnderwritingPrepares the submissions an underwriter decides on, and learns the appetite by watching what gets declined.
- 8:30Work the submission queue. Check each one is complete enough to quote: loss runs, schedules, values, prior carrier.
- 10:00Order inspections and pull loss history. Chase the broker for the three things missing from yesterday's submission.
- 11:30Rate a straightforward renewal in the system and flag the two exposures that changed since last year.
- 13:30Sit in on a referral discussion. This is where you learn why a risk that looks fine on paper is not.
- 15:00Issue endorsements and policy documents, and clear the diary of items due this week.
- 16:30Study. Most assistants are working through CPCU or an AINS module alongside the job.
Claims AdjusterEarly career · ClaimsDecides what happened, whether the policy covers it, and what the company owes.
- 8:00Triage overnight first notices of loss. Severity, coverage questions, and anything with injury goes to the top.
- 9:00Call the policyholder on a new claim. Half of claims work is explaining a process to someone having a bad week.
- 11:00Review an adjuster's report and the photographs, and set or revise the reserve on the file.
- 13:00Coverage question on a file: read the policy wording properly, check the exclusions, document the reasoning.
- 15:00Negotiate a settlement with a represented claimant, or brief counsel on one heading to litigation.
- 16:30Close out files and write the notes. Undocumented reasoning is the thing that costs the company later.
Actuarial AnalystEarly career · ActuarialBuilds the rate indications and reserve estimates the pricing and finance decisions rest on.
- 8:30Refresh the loss triangles with the month's data and check for anything that moved more than it should have.
- 10:00Work on a rate indication for a state filing: trend, loss development, expense provision, credibility weighting.
- 12:30Investigate one segment that is running worse than the model expected. Usually mix, occasionally a real signal.
- 14:00Build the exhibit for the reserve committee pack and explain the movement in plain language.
- 16:00Exam study. Most analysts protect this hour, because progression here is literally measured in exams passed.
Commercial BrokerMid-Level · BrokerageRepresents the client, takes their risk to market, and negotiates the programme that comes back.
- 8:00Review the renewal list. Anything inside ninety days needs a strategy and a market list today.
- 9:30Client call on an upcoming renewal: what changed in their operations, revenue, fleet, payroll, headcount.
- 11:00Build the submission and send it to the markets most likely to have appetite for that class.
- 13:30Negotiate terms with an underwriter: price, retention, sub-limits, and the two exclusions you want removed.
- 15:00Present options to a client and explain honestly what the cheaper programme stops covering.
- 16:30New business development, which is the part of the job that decides your income.
Senior UnderwriterSenior · UnderwritingHolds real authority on difficult accounts and answers for the loss ratio on the book.
- 8:00Read the overnight market news. A competitor withdrawing from a class changes what you will see this week.
- 9:00Work the referral queue: accounts outside junior authority, or outside appetite but worth a hearing.
- 11:00Broker meeting. Relationship work, but also the best intelligence you get on where the market is pricing.
- 13:30Price a complex account and write the rationale. The file has to persuade a reinsurer and an auditor later.
- 15:00Portfolio review with the actuary: what the book is doing, where the growth came from, what it cost.
- 16:30Coach a junior through a declination. Saying no well is most of the craft.
JOB SEARCH
How to Get an Insurance Job in 2026
Insurance hires steadily and explains itself badly. The sector's unemployment rate is 2.1 percent, entry requirements are lower than outsiders assume, and the main obstacle for most candidates is not qualification but knowing which of the four careers inside the industry they are applying for.
Entry-Level
Start Your Insurance Career
What the industry actually is, which first roles exist, and what a hiring manager expects from someone with no track record yet.
What You Should Know About the Field
The shape of the industry, what the first jobs pay, and the one trend changing entry-level hiring.
Insurance is four careers wearing one name
Underwriting prices risk. Claims settles it. Actuarial models it. Brokerage places it for the buyer. These are genuinely different jobs with different skills, different pay curves and different personalities, and the industry rarely explains that to outsiders.
The practical consequence is that the first real interview question is usually which of them you want, and 'insurance' is not an answer. Pick one, learn its vocabulary, and apply into it specifically. You can move later, most often from claims into underwriting, but you cannot start everywhere at once.
Sources: US Bureau of Labor Statistics, Occupational Outlook Handbook: Insurance UnderwritersUS Bureau of Labor Statistics: Claims Adjusters, Appraisers, Examiners and InvestigatorsUS Bureau of Labor Statistics: Insurance Sales AgentsUS Bureau of Labor Statistics: Actuaries
You do not need an insurance degree, and most people do not have one
Federal data puts the typical entry education for claims adjusters and insurance sales agents at a high school diploma, and for underwriters at a bachelor's degree in no particular subject. Risk management and insurance degrees exist and help, but they are a minority of entrants.
What the industry does require is licensing and designations, and those come after you are hired rather than before. Expect a state licence within your first months in claims or distribution, and expect to start a designation in your first year or two.
Sources: US Bureau of Labor Statistics: Claims Adjusters, Appraisers, Examiners and InvestigatorsUS Bureau of Labor Statistics: Insurance Sales AgentsUS Bureau of Labor Statistics, Occupational Outlook Handbook: Insurance UnderwritersUS Bureau of Labor Statistics: Actuaries
The entry salaries, honestly
National medians across all experience levels are $62,280 for insurance sales agents, $78,020 for claims adjusters, examiners and investigators, and $81,370 for underwriters. Entry pay sits below those medians, typically in the high forties to low sixties depending on the function and the city.
Actuarial is the exception in both directions: higher starting pay, but you are also committing to a decade of exams, and employers often expect one or two passed before you graduate.
Sources: US Bureau of Labor Statistics: Insurance Sales AgentsUS Bureau of Labor Statistics: Claims Adjusters, Appraisers, Examiners and InvestigatorsUS Bureau of Labor Statistics, Occupational Outlook Handbook: Insurance UnderwritersUS Bureau of Labor Statistics: Actuaries
Automation is changing which door is open
The federal projections to 2035 expect claims adjusting to shrink by six percent and underwriting by four percent, while actuarial work grows nine percent. That is not the industry contracting, it is routine decisions being automated and judgement work surviving.
For someone entering now it means the high-volume, low-complexity roles are the least safe place to plant a career, and the fastest route out of them is a specialty, a designation, or the analytical side. Entering is still easy; the sector's unemployment rate is 2.1 percent.
Sources: US Bureau of Labor Statistics: Claims Adjusters, Appraisers, Examiners and InvestigatorsUS Bureau of Labor Statistics, Occupational Outlook Handbook: Insurance UnderwritersUS Bureau of Labor Statistics: ActuariesUS Bureau of Labor Statistics, Industries at a Glance: Insurance Carriers and Related Activities
Skills Employers Look For
What a graduate hire is actually assessed on, which is less technical than people expect.
Reading a document properly and saying what it means
A policy is a contract, and most of insurance is working out whether a set of facts falls inside it. The skill is unglamorous: read carefully, notice the defined terms, and resist deciding what it says before you have read the exclusions.
In an interview this shows up as a scenario question. They are watching whether you reach for the wording or for your instinct.
Numeracy without needing to be an actuary
Outside actuarial you do not need advanced mathematics, but you do need to be comfortable with ratios, trends and the arithmetic of exposure: loss ratio, frequency and severity, limits and deductibles, what a rate change does to a premium.
Being able to say what a 65 percent loss ratio means, and why it is not the same as profitability, puts you ahead of most graduate applicants.
Explaining a hard decision to someone having a bad day
Claims especially, but all of it. Policyholders reach you on a bad day, brokers want a decision faster than you can give one, and the explanation has to be plain, accurate and unhurried.
Any job where you handled upset people counts as relevant experience here, and saying so is more persuasive than claiming an interest in risk.
Finishing things, visibly
Early insurance roles are volume roles: queues of submissions, caseloads of files, diaries of tasks due. The people promoted first are the ones whose work does not need checking twice and whose files are documented well enough for someone else to pick up.
It is a quiet skill and it is the one most often cited when managers explain who they moved up.
Interview Questions and Answers
What gets asked of candidates with no insurance experience, and what the question is really testing.
Why insurance?
What they are looking for: Whether you have a real reason, or applied because the posting existed. They have heard 'stability' a thousand times.
I like problems where the answer is defensible rather than obvious. Pricing something before anyone knows what it will cost, then having the loss ratio tell you years later whether you were right, is unusually honest feedback for a desk job.
Make it yours: Name the function you want and one specific thing about it. Vague enthusiasm for the industry reads as no preference.
A customer's claim is denied and they are angry on the phone. What do you do?
What they are looking for: Composure, and whether you understand that the decision and the conversation are separate things.
Let them finish, confirm I understand what happened, then explain which part of the policy drove the decision in plain words. If I am not certain the decision is right, I say I will check rather than defend it on the call.
Make it yours: Use a real example of handling an upset person, from any job. The transferable skill is composure, not insurance.
What is the difference between an insurance broker and an underwriter?
What they are looking for: Basic literacy. Getting this wrong signals you have not done an hour of reading.
The broker acts for the buyer: they structure the risk and take it to market for the best terms. The underwriter acts for the insurer: they decide whether to accept it and at what price. They negotiate against each other, and both need the other to stay in business.
Make it yours: Add which side you want to be on and why. That turns a definition into a career answer.
Tell me about a decision you made with incomplete information.
What they are looking for: Whether you can act under uncertainty and then own the outcome, which is the entire job.
Describe the decision, what you did not know, what you did to narrow it, the call you made, and what you learned when the result came in.
Make it yours: Pick an example where you were partly wrong and say so. Insurance people trust calibrated more than confident.
Mid-Level
Move Up or Move Across in Insurance
How the second job is won: a credential, a specialty, and a loss ratio or a retention number you can speak to.
What You Should Know About the Field
What actually drives the mid-career move, and the two structural choices that shape the rest of it.
Carrier or broker is the choice that defines your pay curve
Carrier roles pay a salary against a book you did not choose and cannot take with you. Brokerage pays less reliably early and far more later, because compensation attaches to a book of business that follows you between firms.
The trade is security against ownership. People who want the technical craft and a predictable life stay carrier side; people who want the upside and can tolerate a revenue number move to broking, usually between years three and eight when they have enough market knowledge to be useful to clients.
Sources: US Bureau of Labor Statistics: Insurance Sales AgentsUS Bureau of Labor Statistics, Occupational Outlook Handbook: Insurance Underwriters
The designation is the gate, and it is worth taking seriously
CPCU is the main property and casualty credential and carries real weight in underwriting and broking. AIC is the claims equivalent, ARM the risk management one, and the actuarial exams are their own decade-long track.
Mid-career is when these stop being optional. Employers fund them, promotion panels ask about them, and the gap between a seven-year underwriter with CPCU and one without is visible in both title and pay.
Sources: The Institutes, CPCU designation requirements (8 courses plus ethics, 18 to 24 months)Society of Actuaries, Associate (ASA) requirementsUS Bureau of Labor Statistics: ActuariesUS Bureau of Labor Statistics: Insurance Sales Agents
Specialty is where scarcity works in your favour
Cyber, marine, energy, professional liability, construction and the excess and surplus market all price risks that do not fit a template, which means fewer people can underwrite or place them. Scarcity of skill is the thing that gives you leverage, in pay and in where you can work.
The route in is almost always lateral: you move into a specialty team one rung below where you are, trade a title for the knowledge, and get it back within two years. Mid-career is the last comfortable window to do that.
Know your own number, because they will ask for it
Underwriters are asked for loss ratio and premium growth on their book. Brokers for retention and new business written. Claims for cycle time, leakage and litigation rate. Actuaries for what they own and sign.
Candidates who cannot quote their own numbers interview badly regardless of how good they are, because the whole industry runs on measured outcomes and not being measured reads as not being trusted.
Skills Employers Look For
The step up from executing well to owning an outcome someone else is relying on.
Pricing or reserving judgement you can defend out loud
At this level the number is yours. What is assessed is not whether you can produce it but whether you can explain the assumptions behind it to a broker who wants it lower or an actuary who thinks it is thin.
The strongest mid-career candidates describe a decision they got wrong, what the data later showed, and what they changed. That is the shape of real judgement.
Working the market rather than waiting on it
Knowing which carriers have appetite this quarter, which are pulling back, where capacity moved after the last renewal season. This is relationship knowledge and it compounds.
It is also the thing that separates a broker who places business from one who merely submits it, and an underwriter who sees the good risks early from one who sees them after three other carriers have passed.
Reading regulation as an operational fact
A rate filing refused in one state, a court widening a coverage definition, a new cyber disclosure rule: each lands as work on someone's desk within weeks. Mid-career is when you are expected to notice before you are told.
Fifty state regulators plus the NAIC means the regulatory surface is genuinely large, and the people who track it are disproportionately useful.
Source: NAIC, McCarran-Ferguson Act and state-based insurance regulation
Handling the account nobody else wants
Difficult accounts are how authority gets extended: the loss-hit renewal, the disputed coverage, the client threatening to move. Volunteering for them early is the most reliable accelerator in the industry.
It also produces the stories that mid-career interviews are made of, which is a second reason to take them.
Interview Questions and Answers
Mid-career interviews test ownership. Expect to be asked for numbers and for a decision that went badly.
Walk me through the loss ratio on your book and what drove it.
What they are looking for: Whether you understand your own results or merely report them. The follow-up is always about what you changed.
Give the number, the trend, and the honest driver: mix, a large loss, rate adequacy, a class that ran hot. Then say what you did about it and what it did next.
Make it yours: Bring real figures. Approximations are fine, but not knowing the direction of travel is disqualifying.
Tell me about a risk you priced or accepted that turned out badly.
What they are looking for: Calibration and honesty. Everyone has one, and candidates who claim otherwise are either junior or evasive.
Describe the account, what you saw, what you missed, what the loss was, and the specific change to how you look at that class now.
Make it yours: Choose one where the reasoning was defensible and the outcome still bad. That is the realistic case.
How do you decide when to walk away from an account?
What they are looking for: Discipline. The expensive mistake in this industry is writing business to hit a growth target.
When the price will not cover the expected loss and expenses at a defensible assumption, or when the information is too thin to form a view and the broker will not fill the gap.
Make it yours: Name a time you declined under pressure to write it. Walking away is the part that needs evidence.
What would you do in your first ninety days here?
What they are looking for: Whether you have thought about this book and this market, rather than reciting a generic plan.
Read the book and the loss history before changing anything, meet the brokers or the claims team, and identify the two or three segments driving the result.
Make it yours: Reference something specific about their market position or recent results. It is public information and almost nobody looks it up.
Senior-Level
Lead an Insurance Function
What changes when the number you answer for is a portfolio, a reserve opinion or a practice, rather than a file.
What You Should Know About the Field
The senior job is capital allocation and judgement under scrutiny, with your name on it.
You are now accountable for a portfolio, not a decision
A senior underwriter answers for how a book performs across a cycle, a chief actuary signs a reserve opinion, a practice leader owns the margin on a whole team's business. The feedback loop lengthens from months to years, which makes judgement harder to prove and easier to lose.
It also means the work becomes structural: appetite, authority limits, reinsurance structure, who you hire. The individual file is now someone else's job and interfering with it is the common failure mode.
The cycle is the thing you are actually managing
Insurance is cyclical in a way most industries are not: capacity floods in after profitable years and prices soften, then withdraws after losses and prices harden. Careers are made by behaving correctly at the turn, which usually means growing when it feels uncomfortable and shrinking when growth is easy.
Senior people are judged on whether they held discipline in a soft market, and almost nobody is rewarded for it at the time.
Source: Insurance Information Institute, Facts + Statistics: US catastrophes (2025, Aon data)
Catastrophe and climate risk have moved from a line item to the strategy
Property pricing, reinsurance cost, state availability crises and the politics of rate adequacy are now the dominant commercial question in large parts of the market. Senior roles in P and C are expected to have a view on exposure concentration and modelled loss, not just on individual accounts.
This is also where the regulatory pressure is sharpest, because availability and affordability are political questions as much as actuarial ones.
Source: Insurance Information Institute, Facts + Statistics: US catastrophes (2025, Aon data)
Regulators and auditors are now part of your audience
Reserve opinions, rate filings, market conduct examinations, solvency reporting. At this level your reasoning is read by people with statutory authority and a different objective from yours.
The practical skill is documenting judgement so that it survives being read two years later by someone who was not in the room and does not share your incentives.
Source: NAIC, McCarran-Ferguson Act and state-based insurance regulation
Skills Employers Look For
Portfolio thinking, hiring, and the ability to be the calm one when the quarter is bad.
Setting appetite and then holding it
Deciding what the business will and will not write, publishing it, and declining the attractive exception. Appetite that bends under pressure is not appetite, and everyone below you learns which it is within a quarter.
Senior candidates are assessed on specific instances of holding the line, ideally ones that cost visible premium.
Building people who can price and settle without you
The constraint on a growing book is almost never capital, it is how many people can exercise judgement unsupervised. Senior leaders are measured on how many underwriters or adjusters they developed to full authority.
It is also the most durable thing you leave behind, and it is the part of the job most often neglected by excellent technicians.
Reading reinsurance as a strategic instrument
What you cede, at what attachment, and what that does to volatility and to the capital the business has to hold. Reinsurance decisions shape what the direct book is able to be.
Senior underwriting and actuarial roles are expected to speak fluently about structure, not just to know that cover exists.
Communicating a bad result without losing the room
Reserve strengthening, a catastrophe quarter, a class that has to be exited. The task is to be early, specific and unflustered, and to arrive with the plan rather than only the number.
This is the skill that separates people who get the next function from people who stay where they are.
Interview Questions and Answers
Senior interviews are about portfolios, cycles and people. Expect to be asked what you would stop doing.
How would you set appetite for this book in the current market?
What they are looking for: Whether you think in portfolios and cycles, and whether you have read their actual position.
Start from where the book sits in the cycle and what the loss history says, name the classes you would grow and the ones you would exit, and tie both to rate adequacy rather than to opportunity.
Make it yours: Say what you would stop writing. Candidates who only describe growth read as untested.
Tell me about a time you had to strengthen reserves or report a bad quarter.
What they are looking for: Integrity and timing. The question behind it is whether you report early or hope it improves.
Describe what you saw, when you escalated, how you explained it, and what changed afterwards in how the signal gets caught sooner.
Make it yours: Emphasise the timeline. Reporting it early is the answer; discovering it late is the failure.
How do you develop underwriters or adjusters to full authority?
What they are looking for: Whether you build capacity or hoard decisions. Technical brilliance that does not scale is a known senior failure.
Give authority in steps against defined classes, review the declines as closely as the acceptances, and make the reasoning the subject of the review rather than the outcome.
Make it yours: Name people you developed and where they are now. It is the most verifiable claim you can make.
What is the biggest risk to this business over the next three years?
What they are looking for: Market literacy and nerve. They want to know whether you will say the uncomfortable thing in an interview.
Pick something real to their book: catastrophe concentration, rate adequacy in a regulated state, social inflation in liability, or reinsurance cost at the next renewal.
Make it yours: Be specific to their lines and geography. A generic answer here wastes the best question they will ask you.
Why Insurance Professionals Need to Stay Informed
AI, new technologies, emerging risks, and changing regulations are reshaping how insurance professionals work and make decisions. Whether you work in underwriting, claims, brokerage, or another area of insurance, staying informed helps you understand where the industry is heading and how your role is evolving.
Read more
The federal projections make the direction concrete: claims adjusting is expected to shrink six percent and underwriting four percent by 2035, while actuarial work grows nine percent. Routine decisions are being automated and judgement work is not. Catastrophe exposure has moved from a line item to the central commercial question in property, state regulators are refusing rate increases that carriers say they need, and capacity moves between classes faster than an annual planning cycle can track.
None of that is secret. It is reported every weekday by a small trade press that writes for practitioners, and read by a fraction of the people whose work depends on it.
The bottom line
The insurance industry is changing fast. Keep your expertise ahead of it.
Rate movements, catastrophe losses, regulatory decisions, reserve charges, new technologies and shifts in capacity all change what your accounts are worth and what your company will write. The people who read the trade press daily are rarely the best technicians in the room, but they are usually the ones who saw it coming.
Stay Informed with Hark's Insurance Briefing
How it works
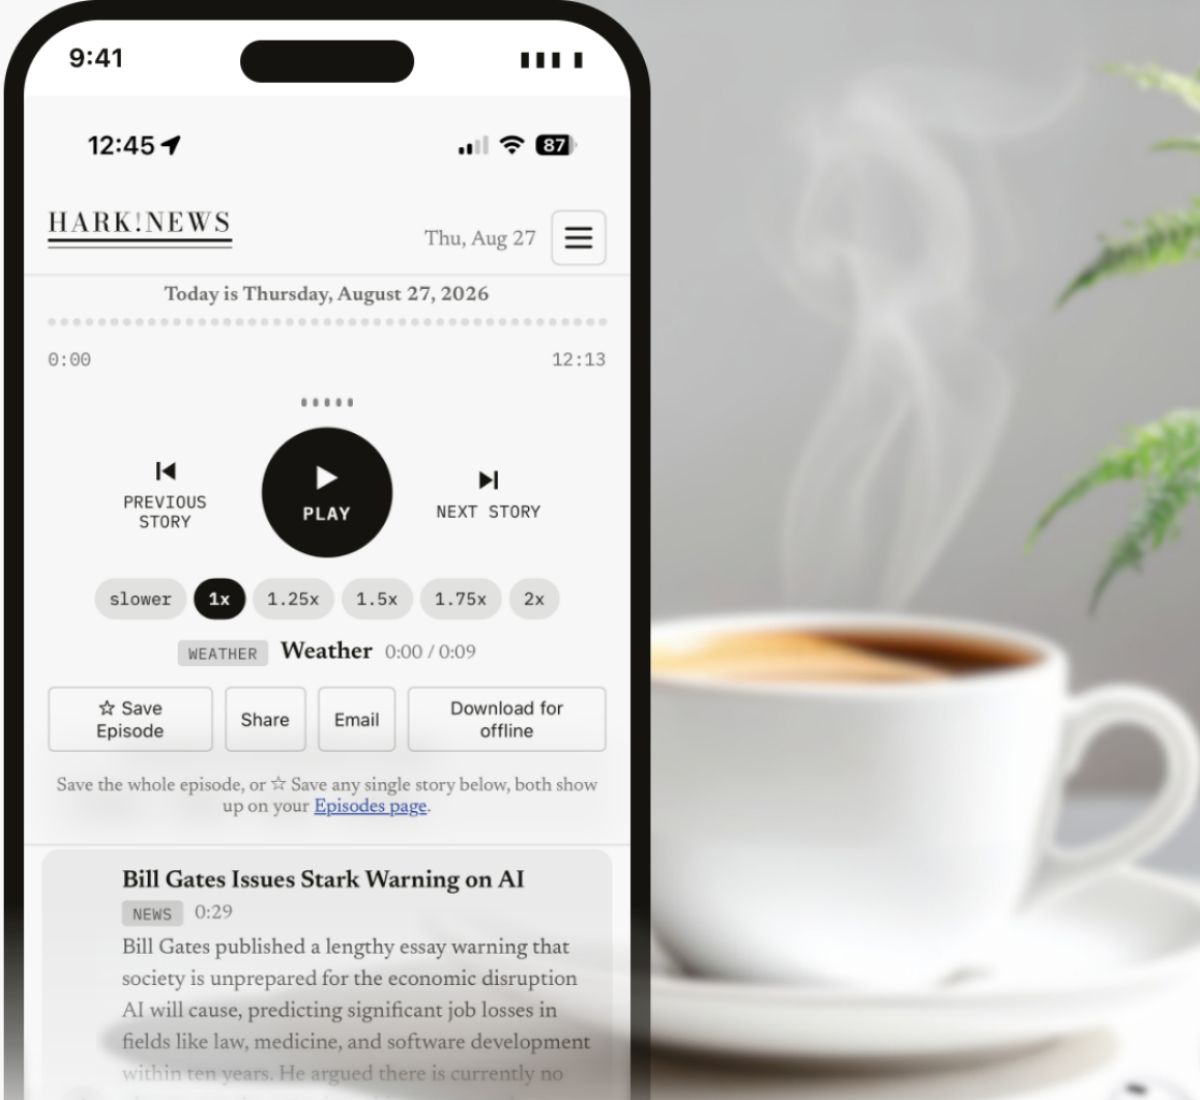
Curated from the best newsletters
Hark's editorial team handpicks the sources worth following. See how we rank
The news that matters in 5 minutes
Hark distills the most important stories into a concise audio briefing.
Texted to you every morning
You set the time and listen when you want.
Go deeper if you want
Upgrade to the 15-minute briefing and select up to 50 newsletters.
The 6 Insurance Newsletters We Handpicked
Insurance Journal Daily Headlines
Wells Media Group (Insurance Journal)
- Free
- Daily
- 100k readers
Free daily morning email from Insurance Journal delivering property/casualty insurance industry headlines in a quick-read format.
Why insurance professionals read it
The industry's default daily. Carrier moves, rate filings, litigation, personnel and catastrophe coverage across property and casualty, written short enough to read before the first meeting. If you only keep one, keep this.
More about this newsletter
Insurance Journal's flagship email, self-described as the industry's favorite daily newsletter, delivers each morning's P/C insurance headlines in an easy-scan format. Published by Wells Media Group, which also runs Claims Journal and Carrier Management; the subscribe page offers a dozen-plus companion newsletters (breaking news, M&A, workers' comp, cyber). All are free.
BestDay
AM Best
- Freemium
- Weekdays
BestDay is AM Best's daily roundup of the key insurance industry stories published by AM Best's news service during the prior business day.
Why insurance professionals read it
AM Best is the rating agency, so this is the one daily written from the solvency and financial strength angle: downgrades, outlooks, results and capital. It tells you which carriers are under pressure before the market reprices them.
More about this newsletter
BestDay compiles breaking industry coverage from AM Best, the insurance ratings agency, into a digest of the prior business day's top stories. It sits on AM Best's news platform (news.ambest.com), where full Best's News article access requires a subscription. Delivery follows the business-day news cycle.
See the other 4 newsletters
Daily Briefing (Business Insurance)
Business Insurance
- Free
- Weekdays
Weekday afternoon roundup of the day's most important commercial insurance and risk management news from trade publication Business Insurance.
Why insurance professionals read it
Written for the commercial and risk management side rather than personal lines: large accounts, captives, workers compensation, liability verdicts and the buyers' view of the market. The best single read if your clients are corporates.
More about this newsletter
Business Insurance's media kit describes the Daily Briefing (M-F) as its largest opt-in email list, delivered every weekday afternoon with a summary of the most important insurance news. The publication covers risk management, risk transfer, and commercial insurance for corporate insurance buyers, brokers, and insurers.
Insurance Business America Newsletter
Key Media (KM Business Information US, Inc.)
- Free
Free email news service from Insurance Business America, Key Media's US insurance trade publication, with breaking news, opinion, and expert analysis for the industry.
Why insurance professionals read it
Distribution's daily: brokers, agencies, MGAs, appointments and the deal flow reshaping who sells what. Strongest on the broking and producer side, which the carrier-focused titles cover thinly.
More about this newsletter
Insurance Business America's newsletter promises the latest breaking news, opinion, and analysis affecting both individual businesses and the wider US insurance industry, spanning P&C, specialty lines, and industry transformation. Signup is a free mailing-list form ('Join our mailing list, it's free!'). The title is part of Key Media's international Insurance Business network.
The Risk Brief
Risk & Insurance
- Free
- Frequent
Risk & Insurance's email briefing The Risk Brief delivers curated top stories on commercial risk and the insurance industry to inboxes most days.
Why insurance professionals read it
Risk and Insurance writes for the corporate risk manager, so it covers the exposures before they become claims: emerging risk, loss prevention, captives and the economics of retention versus transfer.
More about this newsletter
The Risk Brief is Risk & Insurance's flagship email, described on the subscribe page as featuring 'the risk brief and other top stories delivered to your inbox most days.' Risk & Insurance covers commercial risk management, workers' comp, and specialty insurance markets, and offers additional newsletters through the same subscription portal. Signup is free.
Carrier Management Daily Headlines
Wells Media Group
- Free
- Daily
Carrier Management's free Daily Headlines email delivers property/casualty insurance news and analysis for carrier executives, from Wells Media Group.
Why insurance professionals read it
Aimed squarely at carrier executives: strategy, underwriting results, technology adoption and the operating decisions behind the numbers. The most useful of the six if you want to understand how insurers are actually run.
More about this newsletter
The subscribe page offers eight free newsletters, led by Daily Headlines and including This Week's Most Popular, Topic Spotlight, Risk Alerts, Leadership Tips, Editor's Pick, and an Insurtech newsletter. Carrier Management targets P/C carrier C-suites with coverage of underwriting, claims, technology, and market strategy. It is a sister publication to Insurance Journal and Claims Journal in the Wells Media network; signup asks for work email, company, and job title.
You May Also Like
- Best finance newslettersCarriers are institutional investors and rates drive reserves, so the finance desk reads directly into pricing: markets, credit and the macro picture behind your investment income.
- Best climate newslettersCatastrophe exposure is now the central commercial question in property insurance. Climate coverage is where the hazard data, the modelling debate and the availability crises surface first.
- Best real estate newslettersProperty insurance follows the buildings. Construction costs, commercial values and regional housing markets all move what a schedule is worth and what it costs to rebuild.
- Best AI newslettersAutomated underwriting and claims triage are reshaping two of the four careers in this industry. These titles track the tooling and the model risk before vendors reach your desk.
Frequently Asked Questions
Entry-Level
Is insurance a good career?
By the measurable signals, yes. The sector employs about 2.93 million people in the United States and its unemployment rate was 2.1 percent in September 2026, roughly a third of the national figure, which is the clearest evidence of how consistently it hires. Pay is solid rather than spectacular at entry and climbs well with credentials: national medians run from $62,280 for insurance sales agents to $130,000 for actuaries.
The honest caveat is that the industry is sorting. Routine roles are shrinking and judgement roles are growing, so the question is less whether insurance is a good career than which part of it you enter and how quickly you specialise.
What types of careers are available in the insurance industry?
Four main ones, and they are genuinely different jobs. Underwriting decides which risks the company accepts and at what price. Claims investigates losses and settles them. Actuarial models expected losses and sets rates and reserves. Brokerage represents the buyer and places their risk with insurers.
Around those sit risk management inside corporates, loss control and engineering, compliance and regulatory affairs, reinsurance, catastrophe modelling and a growing insurtech sector. Most people enter through one of the four and specialise from there.
Do you need an insurance degree to work in insurance?
No, and most people in the industry do not have one. Federal data lists the typical entry education as a high school diploma for claims adjusters and insurance sales agents, and a bachelor's degree in no specified subject for underwriters. Actuarial is the exception: it expects a quantitative degree and usually one or two exams passed before you graduate.
Risk management and insurance degrees exist and are genuinely useful, but the industry recruits heavily from other fields and teaches the technical content through designations after you are hired.
What are the best entry-level jobs in insurance?
Underwriting assistant, claims associate or trainee adjuster, account coordinator at a brokerage, and actuarial analyst if you have the mathematics. Each is a real apprenticeship into its track rather than a generic administrative job.
If you are undecided, claims teaches you the most about how the product actually behaves, because you see what policies do when tested. It is also the most common route into underwriting later, which makes it a reasonable default first move.
Mid-Level
What is the difference between underwriting, claims, brokerage, and actuarial careers?
Underwriting is a pricing and selection job: you decide what to accept, on what terms, and you answer for the loss ratio on your book. Claims is an investigation and settlement job: you establish facts, apply the policy and set reserves. Actuarial is a modelling job: you produce the rates and reserves the other two depend on, behind a long exam track. Brokerage is a client and market job: you act for the buyer and are paid against a book of business.
The practical differences are pay shape and portability. Carrier roles pay salaries against books you cannot take with you; broking pays less early and far more later, because the book follows you.
Which insurance careers require licenses or professional certifications?
Insurance sales agents must be licensed in every state where they work. Claims adjuster licensing varies: some states require prelicensing education and an exam, others few requirements, and in some states employed adjusters can work under the company's licence rather than their own. Underwriting requires no licence, though employers expect designations.
The designations that carry weight are CPCU for property and casualty generally, AIC for claims, ARM for risk management, and the SOA or CAS exam tracks for actuaries. Associate-level actuarial certification can take up to seven years, with fellowship several years beyond that.
How much can you earn in an insurance career?
National medians from May 2025 are $62,280 for insurance sales agents, $78,020 for claims adjusters, examiners and investigators, $81,370 for insurance underwriters, and $130,000 for actuaries. Those are medians across all experience levels, so entry pay sits below them and senior pay well above.
Two things move you up the range faster than time: a designation, and a specialty where few people can price the risk. Brokerage has the widest spread of all, because compensation attaches to a book of business rather than to a grade.
What is the difference between working for an insurance carrier and an insurance broker?
A carrier takes the risk onto its own balance sheet, so carrier roles are about selection, pricing and managing a portfolio you were assigned. A broker acts for the buyer, so broking roles are about relationships, market knowledge and negotiating terms against underwriters.
Culturally the carrier side is more technical and more stable, the broking side more commercial and more variable. The pay difference is the honest deciding factor: brokers build a portable book and earn against it, carrier staff do not.
Senior-Level
Can you build an insurance career without working in sales?
Yes, and most of the industry does. Underwriting, claims, actuarial, risk management, compliance, catastrophe modelling and reinsurance analysis involve no selling at all. Insurance sales agents are the largest single occupation at 572,600 jobs, which is why outsiders assume the industry is a sales industry, but they are a minority of the 2.93 million people it employs.
If you want client contact without a revenue target, claims and risk management both offer it. If you want none, actuarial and underwriting are the clearest routes.
How is AI changing careers in insurance?
It is automating routine decisions and leaving the contested ones. Straight-through processing handles simple claims end to end, submission triage and data capture no longer need a person, and rating engines price standard risks without referral. The federal projections to 2035 reflect it directly: claims adjusting down six percent, underwriting down four percent, actuarial up nine percent.
What is not being automated is judgement under scrutiny: disputed coverage, loss-hit renewals, complex liability, new exposures with no credible data. The career implication is that high-volume roles are a good place to start and a poor place to stay.
What does a senior underwriter actually answer for?
The performance of a portfolio across a cycle, not a set of individual decisions. That means appetite, authority limits, the reinsurance structure sitting behind the book, and who on the team is trusted with what.
The hard part is that the feedback loop runs in years. A book written in a soft market looks excellent for two years and then does not, which is why senior people are judged on whether they held pricing discipline when growth was easy rather than on last quarter's premium.
Is catastrophe and climate risk changing senior insurance roles?
Substantially, in property and casualty especially. Exposure concentration, modelled loss and reinsurance cost have moved from technical inputs to the central commercial question, and availability in exposed states is now a political argument as much as an actuarial one.
For senior roles that means being able to hold a view on accumulation and modelling assumptions, and being able to explain a rate need to a regulator whose objective is affordability rather than solvency. It is the clearest growth area in senior P and C hiring.
Get Tomorrow's Insurance Briefing
Six sources, one briefing, five minutes a morning. Enough to know what moved in rates, catastrophe losses and regulation before your first meeting.