Fintech & Payments Career Guide
Explore careers in fintech and payments, including jobs, salaries, and career paths. Get interview tips and stay current on fintech news, AI, regulation, and payment technologies.
The Top Fintech & Payments News, in 5 Minutes.
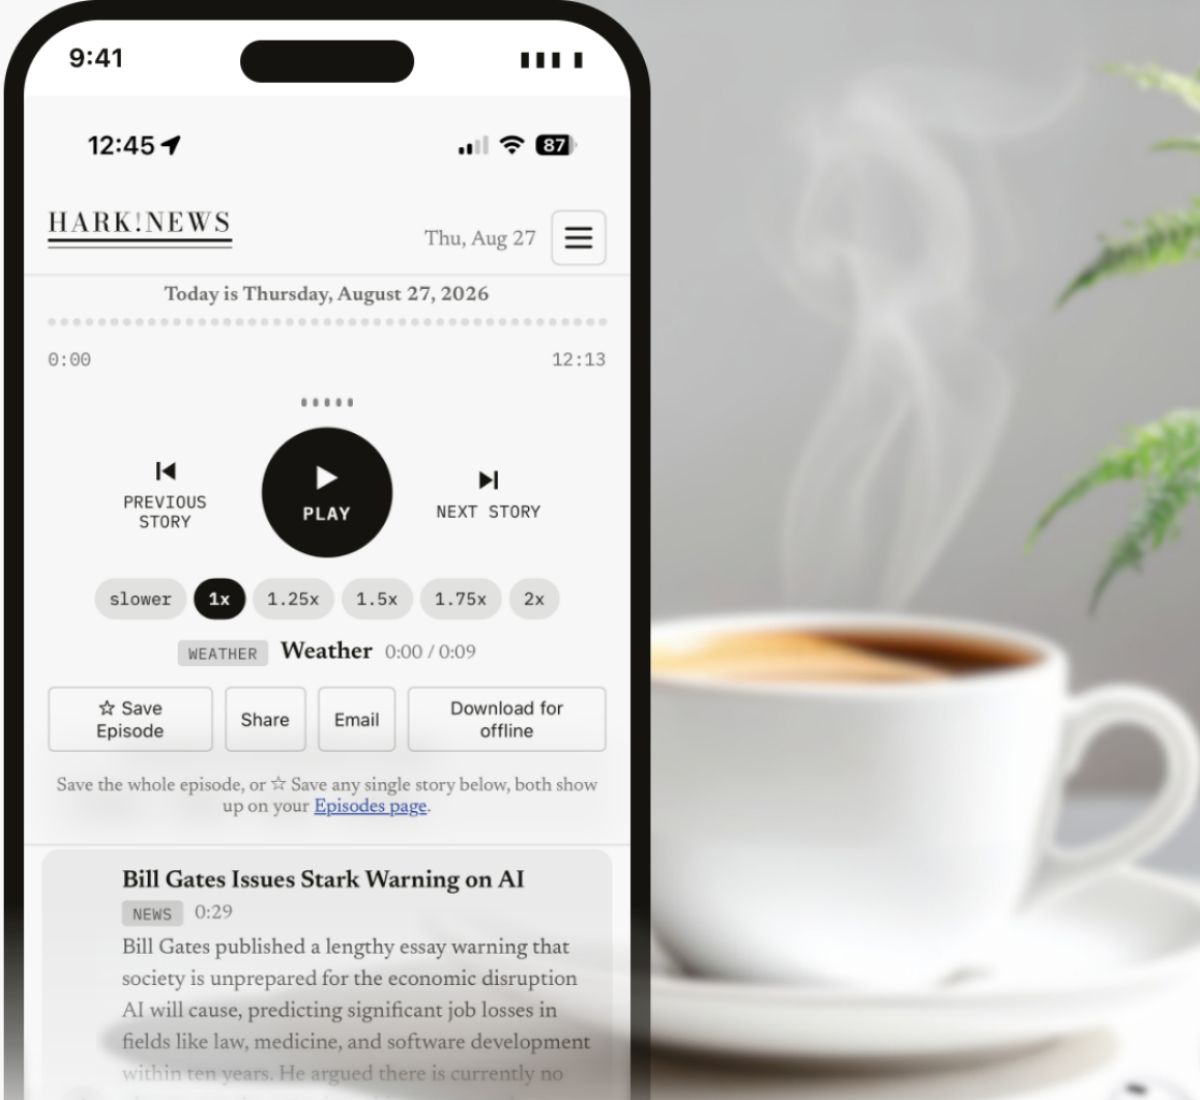
We handpick the best fintech and payments newsletters and distill key news and insights into a 5-minute audio briefing, texted to you every morning.
Try the Fintech & Payments BriefingFree
At a glance
Fintech & Payments at a Glance
There is no federal occupation code for fintech, because it is a sector rather than a job, and the work is counted across the codes its functions belong to: 879,700 financial managers at a median of $166,570, 443,100 financial analysts at $103,570, 1.9 million software developers at $135,980, 531,000 securities and financial services sales agents at $78,660, and the technology managers who run much of it at $175,140.
The misconception worth correcting is that this is a sector for engineers. It is not. Product managers decide what a regulated product may be, risk analysts set the dials on fraud and credit, compliance and financial crime teams own obligations with headcount attached, operations handle disputes and reconciliation, partnerships manage the sponsor bank, and treasury decides whether the business can grow. Several hire people with no technical background, and the control functions recruit from banking, regulators and law.
Pay rises fastest for people who can hold a commercial case and a regulatory constraint in the same sentence, which is rarer than it sounds. Entry generally happens through a function rather than through the sector: you come in as an analyst, an engineer or an operations hire, and learn the payments and regulatory fluency in the first six months. That fluency compounds, because it travels across lending, payments, wealth and infrastructure, and because instant rails, embedded finance and AI keep changing what a product is allowed to be.
The numbers that matter
879,700
Financial manager jobs in the United States (2025)U.S. Bureau of Labor Statistics
$166,570
Median annual pay for financial managers (May 2025)U.S. Bureau of Labor Statistics
+10%
Projected growth for financial managers, 2025 to 2035U.S. Bureau of Labor Statistics
443,100
Financial analyst jobs in the United States (2025)U.S. Bureau of Labor Statistics
Job titles
- Payments Operations Analyst
- Risk Analyst
- Product Manager
- Compliance Officer
- Partnerships Manager
- Head of Payments
Who hires
- Fintech startups
- Payment processors
- Card networks
- Banks and credit unions
- Infrastructure providers
- Regulators and consultancies
Credentials
- Bachelor's degree (typical)
- Anti-money-laundering certification
- Payments professional qualification
- SQL
- Regulatory literacy
- Unit economics
Where fintech careers are built
Payments
Moving value between parties, and the economics of doing it.
Lending and credit
Underwriting, capital and collections. A different governing risk.
Risk and financial crime
Fraud, monitoring and the obligations that come with a licence.
Compliance and licensing
What the product is allowed to be, decided before it is built.
Partnerships and banking
The sponsor bank, the processor and the network. Fragile and strategic.
Infrastructure
The APIs other companies embed. Where margin is moving.
Fintech & Payments Jobs & Salaries
Fintech has no federal occupation code, so the table uses the codes its functions are counted under. Read it as a map of the sector's pay bands rather than a ladder: a product manager, a risk lead and an engineer at the same company appear on different rows of it.
Securities and financial services sales agents
$78,660
Financial analysts
$103,570
Software developers
$135,980
Financial managers
$166,570
Computer and information systems managers
$175,140
Source: US Bureau of Labor Statistics, Occupational Outlook Handbook (May 2025 pay, 2025 to 2035 projections), May 2025 pay data.
Fintech & Payments Career Paths
Three ladders that hire differently and converge at the top. The commercial track owns revenue and partners, the risk and control track owns what the firm is permitted to do, and the technical track owns the systems. Senior roles here usually go to people fluent in more than one.
- Analyst or Associate0 to 3 yearsVolume, pricing and the reporting nobody else wants
- Product Manager3 to 6 yearsA product line and the partners it depends on
- Senior Product Manager6 to 10 yearsEconomics, roadmap and the regulatory trade-offs
- Head of Product or Payments10 or more yearsWhat the company builds, buys or refuses
Credential that fits No required credential; payments fluency and a track record of shipped regulated products
The salary table uses federal occupation codes rather than fintech titles, because there is no code for this sector. Three people on the same product team can appear on three different rows of it.
A Typical Day in Fintech & Payments Jobs
Four roles drawn from different functions, ordered from the most junior to the most senior, to show how differently the same company's day looks depending on where you sit. The schedules are representative composites.
Payments Operations AnalystEntry-LevelWhere the exceptions land. The best first job in the sector for learning how money actually moves.
- 8:00Check the overnight settlement files and the two that did not balance
- 9:30Work the exception queue: failed payouts, returns, duplicates
- 11:00Chase the processor about a batch that is still pending
- 13:00Chargeback representments, with evidence attached properly
- 15:00Reconcile the ledger against the bank statement line by line
- 16:30Write up the recurring break so somebody can fix the cause
Risk AnalystMid-LevelSets the dials. Judged on two numbers that move in opposite directions.
- 8:30Overnight fraud rate and approval rate, together, never separately
- 9:30Investigate the cluster that appeared on one merchant category
- 11:00Draft a rule change, then model what it rejects that is good
- 13:00Review with compliance, because a rule can be discriminatory
- 15:00Ship the rule behind a limit, and watch it for an hour
- 16:30Update the loss forecast the finance team builds on
Product ManagerMid-LevelDecides what the product is allowed to be, which is a different job here.
- 8:30Read the overnight trade press for anything that moves the perimeter
- 9:30Scope a feature with compliance in the room from the first draft
- 11:00Sponsor bank call about a change they need to approve
- 13:00Unit economics: what this costs per transaction at ten times volume
- 15:00Engineering review of the reconciliation design, not the happy path
- 16:30Write the decision down, with the regulatory reasoning attached
Head of PaymentsSenior-LevelOwns the rails, the partners and the cost of moving every pound and dollar.
- 7:30Scan enforcement news and scheme bulletins before anything else
- 9:00Processor negotiation, where basis points are the whole conversation
- 10:30Review the rail strategy as instant payments change the economics
- 13:00Board paper on the cost of risk and why it is not fixed
- 15:00Contingency planning for losing a banking partner
- 16:30Hiring: a compliance lead who can move at product speed
Job guide
How to Get a Job in Fintech & Payments in 2026
What the sector asks of you, the skills employers screen for, and the questions you will be asked. The three tabs split the same guide by experience, because what gets an operations analyst hired is not what gets a head of payments hired.
Entry-Level
Breaking Into Fintech & Payments
Come in through a function rather than through the sector. Operations and risk analysis are underrated first jobs, because the exceptions queue teaches you how money moves faster than any course will.
What to Know About the Sector
The facts that should shape your first applications.
Several of the Best Routes In Are Not Technical
Risk, compliance, financial crime, operations and partnerships all hire people with no engineering background, and the control functions specifically hire from banks, regulators and law. Financial analysts, one of the codes this work sits under, number 443,100 and grow 7 percent to 2035 with about 29,500 openings a year.
Fintech Is a Sector, Not an Occupation
The federal data counts the work across the functions it employs: 879,700 financial managers at $166,570, 443,100 financial analysts at $103,570, 1.9 million software developers at $135,980 and 531,000 securities and financial services sales agents at $78,660. You enter through a function rather than through the sector, which is why advice aimed at the sector as a whole is usually useless.
Sources: US Bureau of Labor Statistics, Financial ManagersUS Bureau of Labor Statistics, Financial AnalystsUS Bureau of Labor Statistics, Software Developers, Quality Assurance Analysts, and TestersUS Bureau of Labor Statistics, Securities, Commodities, and Financial Services Sales Agents
The Sector Is Cyclical in a Way the Codes Do Not Show
Federal projections describe occupations, not funding conditions. Fintech hiring moves with interest rates and venture funding, so a sector growing on paper still contains companies cutting a third of their staff in a quarter. The practical protections are payments and regulatory fluency, which travel, and an employer with revenue rather than only a runway.
Sources: US Bureau of Labor Statistics, Financial ManagersUS Bureau of Labor Statistics, Software Developers, Quality Assurance Analysts, and Testers
The Pay Follows Judgement, Not Function
Financial managers sit at a median of $166,570 and computer and information systems managers at $175,140, both with five years or more of experience listed as typical entry. Both sit well above the individual contributor codes, and in this sector the people who reach them are usually the ones who can argue a commercial case and a regulatory constraint at the same time.
Sources: US Bureau of Labor Statistics, Financial ManagersUS Bureau of Labor Statistics, Computer and Information Systems Managers
Skills Employers Hire For
What actually gets a first fintech job.
Knowing How Money Actually Moves
Authorisation against settlement, interchange and who pays it, ACH against instant rails, and why a chargeback arrives months later. Rare on arrival, learnable in months, and the single most portable thing in the sector.
SQL and Comfort With Data
Every function here is measured on numbers somebody has to pull. Waiting for an analyst to answer a question about your own product is a career ceiling.
Regulatory Literacy
Not legal expertise. Knowing which rules apply to your product, what a licence permits, and when to bring in someone who does know. The difference between a fast team and a reckless one.
Reconciliation Thinking
Designing for the case where the network times out after the money moved. Payments systems are judged on whether the ledger balances, not on whether the API returned a 200.
Interview Questions and Answers
What you will be asked as a junior or a career changer.
Walk me through what happens between a card tap and the merchant being paid.
What they are looking for: Whether you have the fluency or only the vocabulary.
Authorisation first, which is a hold rather than a movement, then clearing, then settlement, with interchange and scheme fees taken along the way and the merchant paid net, usually a day or more later.
Make it yours: Say where the money actually is at each step. That is what separates real knowledge from a glossary.
Why fintech rather than a bank, or a technology company?
What they are looking for: Whether you understand the trade you are making.
I want the constraint to be part of the problem. A bank has the constraint without the speed, a technology company has the speed without the constraint.
Make it yours: Avoid criticising banks. Half your future colleagues will have come from one.
Tell me about a time compliance blocked you.
What they are looking for: Whether you treat the control function as an adversary.
They were right, and we had scoped it without them. We changed the process so a control owner joins at the first draft, which has been faster overall even though each review is slower.
Make it yours: A story where compliance was wrong and you won reads badly here. Choose carefully.
Who is your sponsor bank and how concentrated are you?
What they are looking for: This one is yours to ask them.
The answer tells you how much regulatory risk sits outside the company's control, and whether anyone has thought about losing it.
Make it yours: Ask what the contingency is. A company with no answer is telling you something.
Mid-Level
Advancing in Fintech & Payments
The middle is where the two halves have to meet. Mid-level people are hired for the ability to argue economics and regulation at once, and the ones who can only do one get stuck.
What to Know About the Sector
What shapes the move from analyst to owner.
Compliance Is a Product Constraint, Not a Review Stage
Licensing decides what the product may be at all, and financial crime obligations arrive with operational headcount attached. Products designed to a deadline and shown to compliance at the end get rebuilt, which is why the functional pattern that works puts a control owner in the room while the thing is being scoped.
The Pay Follows Judgement, Not Function
Financial managers sit at a median of $166,570 and computer and information systems managers at $175,140, both with five years or more of experience listed as typical entry. Both sit well above the individual contributor codes, and in this sector the people who reach them are usually the ones who can argue a commercial case and a regulatory constraint at the same time.
Sources: US Bureau of Labor Statistics, Financial ManagersUS Bureau of Labor Statistics, Computer and Information Systems Managers
The Sector Is Cyclical in a Way the Codes Do Not Show
Federal projections describe occupations, not funding conditions. Fintech hiring moves with interest rates and venture funding, so a sector growing on paper still contains companies cutting a third of their staff in a quarter. The practical protections are payments and regulatory fluency, which travel, and an employer with revenue rather than only a runway.
Sources: US Bureau of Labor Statistics, Financial ManagersUS Bureau of Labor Statistics, Software Developers, Quality Assurance Analysts, and Testers
Several of the Best Routes In Are Not Technical
Risk, compliance, financial crime, operations and partnerships all hire people with no engineering background, and the control functions specifically hire from banks, regulators and law. Financial analysts, one of the codes this work sits under, number 443,100 and grow 7 percent to 2035 with about 29,500 openings a year.
Skills Employers Hire For
What hiring managers read at this level.
Unit Economics to the Basis Point
Margins here are thin enough that cost per transaction decides strategy. People who cannot state theirs make confident decisions that lose money at scale.
Fraud and Credit Fundamentals
Loss rates as a dial rather than a target of zero, and the discipline of reading approval rate alongside it. Optimising either alone is the commonest expensive mistake in the sector.
Reconciliation Thinking
Designing for the case where the network times out after the money moved. Payments systems are judged on whether the ledger balances, not on whether the API returned a 200.
Writing for a Regulator
Stating a decision, its basis and its evidence in a way a supervisor can follow. An underrated skill that marks out the people who get promoted into the control functions.
Interview Questions and Answers
What a mid-level loop turns on.
Our fraud rate is too high. What do you do?
What they are looking for: Whether you optimise one number in isolation.
I look at approval rate at the same time, because driving fraud to zero usually costs more in rejected good customers than the fraud did. Then I find where the losses are concentrated before touching a rule.
Make it yours: Insist on the second number unprompted. Candidates who do not are an expensive hire.
How would you price this product?
What they are looking for: Unit economics, including the costs people forget.
Cost of goods is interchange, scheme and processing. Cost of risk is fraud, chargebacks and credit. Cost of compliance scales with volume more than people model it to.
Make it yours: Name the compliance cost. Most candidates treat it as fixed and it is not.
A regulator asks why this customer was declined. What can you show them?
What they are looking for: Whether you think about explainability before deployment.
The rule or model version, its inputs, the threshold, who approved it, and the review path the customer had. If I cannot produce that, the control is not deployable regardless of its performance.
Make it yours: Answer with the artefact, not the intention. Regulators ask for evidence.
What breaks if volume goes up tenfold?
What they are looking for: Whether you think in failure modes.
Reconciliation first, then the manual review queue, then the partner's limits. Systems usually scale; the operations and the control functions are what do not.
Make it yours: The non-technical answers are the good ones. Most candidates only name infrastructure.
Senior-Level
Leading in Fintech & Payments
Senior roles are judged on the risks you chose not to take and the partnerships you kept. The work is appetite, licences, economics at scale and the conversations with the people who can switch your business off.
What to Know About the Sector
What the senior market rewards.
The Pay Follows Judgement, Not Function
Financial managers sit at a median of $166,570 and computer and information systems managers at $175,140, both with five years or more of experience listed as typical entry. Both sit well above the individual contributor codes, and in this sector the people who reach them are usually the ones who can argue a commercial case and a regulatory constraint at the same time.
Sources: US Bureau of Labor Statistics, Financial ManagersUS Bureau of Labor Statistics, Computer and Information Systems Managers
Compliance Is a Product Constraint, Not a Review Stage
Licensing decides what the product may be at all, and financial crime obligations arrive with operational headcount attached. Products designed to a deadline and shown to compliance at the end get rebuilt, which is why the functional pattern that works puts a control owner in the room while the thing is being scoped.
The Sector Is Cyclical in a Way the Codes Do Not Show
Federal projections describe occupations, not funding conditions. Fintech hiring moves with interest rates and venture funding, so a sector growing on paper still contains companies cutting a third of their staff in a quarter. The practical protections are payments and regulatory fluency, which travel, and an employer with revenue rather than only a runway.
Sources: US Bureau of Labor Statistics, Financial ManagersUS Bureau of Labor Statistics, Software Developers, Quality Assurance Analysts, and Testers
Fintech Is a Sector, Not an Occupation
The federal data counts the work across the functions it employs: 879,700 financial managers at $166,570, 443,100 financial analysts at $103,570, 1.9 million software developers at $135,980 and 531,000 securities and financial services sales agents at $78,660. You enter through a function rather than through the sector, which is why advice aimed at the sector as a whole is usually useless.
Sources: US Bureau of Labor Statistics, Financial ManagersUS Bureau of Labor Statistics, Financial AnalystsUS Bureau of Labor Statistics, Software Developers, Quality Assurance Analysts, and TestersUS Bureau of Labor Statistics, Securities, Commodities, and Financial Services Sales Agents
Skills Employers Hire For
What an executive search screens for.
Partner Management
The sponsor bank, the processor and the network each take a cut and each hold a veto. Treating those relationships as commodities is how companies discover that switching one takes a year.
Unit Economics to the Basis Point
Margins here are thin enough that cost per transaction decides strategy. People who cannot state theirs make confident decisions that lose money at scale.
Writing for a Regulator
Stating a decision, its basis and its evidence in a way a supervisor can follow. An underrated skill that marks out the people who get promoted into the control functions.
Regulatory Literacy
Not legal expertise. Knowing which rules apply to your product, what a licence permits, and when to bring in someone who does know. The difference between a fast team and a reckless one.
Interview Questions and Answers
What an executive panel asks.
Which risk would actually end this company?
What they are looking for: Senior judgement about what matters.
Losing the banking relationship. An enforcement action is survivable and slow; a sponsor bank withdrawing is fast and final, and there is rarely a queue of replacements.
Make it yours: Credit and fraud are the expected answers. The partner answer marks you as senior.
Build, buy or partner for the licence?
What they are looking for: Commercial and regulatory reasoning together.
Partner first in almost every case, because it gets you inside somebody's perimeter now. Building means capital, a compliance organisation and years, which only pays back at volume.
Make it yours: Name what you give up by partnering: economics and control, plus concentration risk.
What breaks if volume goes up tenfold?
What they are looking for: Whether you think in failure modes.
Reconciliation first, then the manual review queue, then the partner's limits. Systems usually scale; the operations and the control functions are what do not.
Make it yours: The non-technical answers are the good ones. Most candidates only name infrastructure.
Who is your sponsor bank and how concentrated are you?
What they are looking for: This one is yours to ask them.
The answer tells you how much regulatory risk sits outside the company's control, and whether anyone has thought about losing it.
Make it yours: Ask what the contingency is. A company with no answer is telling you something.
Why Fintech & Payments Professionals Need to Stay Informed
AI, real-time payments, stablecoins, digital wallets, and embedded finance are reshaping financial services. As regulations evolve and new competitors emerge, staying informed helps fintech and payments professionals spot opportunities, anticipate disruption, and make smarter decisions in a rapidly changing industry.
The bottom line
Fintech Is Transforming Fast. Stay Ahead.
The functions this sector hires into are growing steadily, financial managers 10 percent to 2035, software developers 10 percent, and the sector itself moves faster than any of them. The people who do well build payments and regulatory fluency early, because it is what lets them move between companies when the funding cycle turns.
Stay Informed with Hark's Fintech & Payments Briefing
How it works
Pick the newsletters you want
Choose from our handpicked list, or add your own. See the picks
We subscribe you properly
Each one arrives at your own private Hark address, never your inbox.
We read them so you do not have to
Every issue is distilled into one short script each morning.
You listen on the way in
A text arrives with a link. Five minutes, then you are current.
The 6 Fintech & Payments Newsletters We Handpicked
This Week in Fintech
This Week in Fintech (Nik Milanović)
- Free
- Weekly
- 225k readers
Free weekly roundup of global fintech news (funding rounds, M&A, product launches, and policy) founded by investor Nik Milanović, with regional editions.
Why fintech & payments professionals read it
The sector's community newsletter and the best weekly overview, strongest on who is doing what and on the funding that decides which companies are still here next year.
More about this newsletter
Weekly curated digests of fintech financings, exits, launches, and policy news, split into regional editions covering the US, UK and Europe, Latin America, Africa, Asia and India, China, and MENA, plus topical letters on stablecoins, fraud, and policy. Founder Nik Milanović previously worked at Google Pay, Petal, and Funding Circle and runs the affiliated Fintech Fund. Entirely free; the site claims 225,000+ subscribers.
FinTech Futures Newsletter
FinTech Futures (Informa)
- Free
- Daily
- 35k readers
Free daily email from FinTech Futures, Informa's fintech and banking-technology news site, with top stories, analysis, white papers, and event highlights.
Why fintech & payments professionals read it
Daily trade reporting with unusually good coverage of the vendor and core banking end, which is where most of the actual implementation work in this sector happens.
More about this newsletter
Daily handpicked fintech and banking-tech news plus a weekly digest option, drawn from FinTech Futures' global newsroom coverage of core banking, payments, and fintech vendors. Registration is free with customizable frequency. The signup form cites a community of 35,000+ fintech professionals; site marketing elsewhere claims 90,000+ newsletter subscribers.
See the other 4 newsletters
Finextra Daily Newsletter
Finextra Research
- Free
- Weekdays
Daily fintech news digest from Finextra Research, the London-based newswire covering banking technology, payments, and financial-services innovation.
Why fintech & payments professionals read it
The most international of the six, and the one that keeps European and instant payments developments in view rather than treating the United States as the whole market.
More about this newsletter
Finextra's daily newsletter goes out five times a week with the wire's coverage of retail and wholesale banking technology, payments, cloud, AI, and blockchain. Subscribers register as free Finextra community members and can customize topic preferences. Finextra is one of the longest-running fintech news outlets.
Payments Dive: Daily Dive
Industry Dive
- Free
- Weekdays
Daily newsletter from Industry Dive covering the payments industry: retail and B2B payments, banking, regulation, risk, and technology.
Why fintech & payments professionals read it
Payments specifically, daily, with the strongest coverage of card networks, interchange, regulation and the unit economics of moving money, which the broader fintech titles treat as background.
More about this newsletter
Payments Dive's Daily Dive delivers the payments beat each weekday (card networks, processors, fintech entrants, regulation, and B2B payments) reported by Industry Dive's staff journalists. Free to subscribe with an email address.
Fintech Business Weekly
Jason Mikula
- Free
- Weekly
- 93k readers
Weekly Substack by fintech advisor Jason Mikula offering in-depth, often investigative analysis of banking-as-a-service, fintech, and crypto regulation stories.
Why fintech & payments professionals read it
The most sceptical read on the list. Follows sponsor bank relationships, enforcement and the things that go wrong, which is the coverage most likely to affect your product.
More about this newsletter
One long-form issue a week digging into fintech and banking stories (BaaS failures, regulatory enforcement, neobank economics) with a reputation for original investigative reporting, 'without fear or favor.' Mikula is an independent fintech and banking advisor, author of the book Banking as a Service, with prior stints at Goldman Sachs, Enova, and LendUp. The Substack shows 93,000+ subscribers.
Tearsheet Daily Newsletter
Tearsheet
- Free
- Daily
Daily digest from fintech media company Tearsheet summarizing top stories in modern finance: new products, launches, and partnerships.
Why fintech & payments professionals read it
Covers the incumbent side, what banks are building and buying, which is the half of the market a fintech-only diet misses entirely.
More about this newsletter
Tearsheet's daily newsletter gives short summaries of the day's top stories in fintech and financial services (product launches, partnerships, and industry moves) alongside a flagship weekly edition. Tearsheet is a New York fintech media company; the daily and weekly emails are free, while a paid Pro membership adds industry briefs and the 10-Q earnings newsletter.
You May Also Like
- Commercial BankersThe incumbent side of the same market, and the sponsor relationships most fintech products depend on. Reading both is how you see a deal from each end.
- Product ManagersWhere much of the sector's decision-making actually sits, since a regulated product's scope is set by what the licence and the partner bank will allow.
- Software EngineersFintech engineering counted under the federal developer code, at a median of $135,980, with the added constraint that your bugs move money.
- Venture CapitalistsWhose funding decisions set the sector's hiring cycle. Worth following because a closed window shows up in headcount months before it shows up in the news.
Frequently Asked Questions
Entry-Level
What is fintech, and what types of careers are available in fintech and payments?
Fintech is financial services built and staffed like a technology company, and payments is the plumbing most of it runs on. The careers inside it are more varied than the label suggests: engineering and product, certainly, but also risk and fraud analysis, compliance and financial crime, operations, partnerships, treasury and sales. What they share is that the product moves other people's money, so every decision carries a regulatory consequence and a loss that somebody has to bear.
Is fintech a good career, and what is the long-term job outlook?
Treat it as a sector you enter through a function rather than as one career with one outlook. The functions it hires into are healthy on the federal numbers: financial managers number 879,700 and grow 10 percent to 2035 at a median of $166,570, financial analysts 443,100 and 7 percent at $103,570, software developers 1.9 million and 10 percent at $135,980. The sector is cyclical in a way those projections do not capture, because funding conditions and interest rates move hiring, so plan for a career made of several employers.
How do you get a job in fintech or payments with no industry experience?
Come in through what you already do. Engineers are hired as engineers and analysts as analysts, and the fintech-specific knowledge is learned in the first six months on the job. The genuine shortcut for a career changer is operations or risk analysis, where the exceptions queue teaches you how money actually moves faster than any course, and which is the most common internal feeder into product, compliance and payments roles.
Do you need a finance, business, or computer science degree to work in fintech?
No single degree is required and no single degree is sufficient. BLS lists a bachelor's as typical entry for the financial analyst, financial manager and software developer codes this work sits under, and employers in practice care more about whether you can read your own numbers and understand the rules that apply to your product. The control functions are the clearest exception in a useful direction: they hire from banking, from regulators and from law, and value that background above any degree subject.
What skills do employers look for when hiring fintech and payments professionals?
Fluency in how money moves, which is unusual because almost nobody arrives with it: authorisation against settlement, interchange and who pays it, how instant rails differ from batch ones, and why a chargeback can arrive months later. Then unit economics to the basis point, because margins here are thin. Then SQL, because every function is measured on numbers somebody has to pull, and enough regulatory literacy to know which rules apply and when to call someone who knows more.
What are the best entry-level jobs in fintech and payments?
Payments operations analyst, risk analyst, onboarding or financial crime analyst, implementation consultant, and customer support at a company whose product is complicated. All five put you close to the failure cases, which is where the learning is. Beyond those, graduate programmes at processors, networks and banks are a real route, and engineering roles at any company with a public API count as fintech entry even if the job advert never uses the word.
What is the difference between working in fintech, traditional banking, and the payments industry?
Banking is the regulated balance sheet, with a licence, capital requirements and a supervisory relationship. Fintech is usually a technology company operating inside somebody else's regulatory perimeter, typically a sponsor bank's, which buys speed and costs control. Payments is a function that exists inside both, and is the most portable specialism of the three, because every product in financial services eventually has to move money.
Mid-Level
How much do fintech and payments professionals earn at different career levels?
The federal codes give the shape rather than the titles. Securities and financial services sales agents sit at a median of $78,660, financial analysts at $103,570, software developers at $135,980, financial managers at $166,570, and computer and information systems managers at $175,140. A fintech analyst typically tracks the analyst row, a product or risk lead the manager rows, and equity compensation at venture-backed companies sits on top of all of it with a correspondingly wide range of outcomes.
How do you prepare for a fintech or payments job interview?
Expect a case rather than a quiz. The common shape is a product or market question: how would you price this, where does the fraud risk sit, what breaks if volume goes up tenfold. Interviewers are checking whether you reason about unit economics and regulation together, because candidates who think about only one of the two are the expensive hires. Bring one number you moved, and be ready to say what the counterfactual was.
What are the best fintech companies to work for, and how do you evaluate career opportunities?
Evaluate the regulatory position before the product. Ask who the sponsor bank is and how concentrated the company is on it, whether revenue exists or only a runway, and what the loss rates look like. A company with real revenue and a diversified partner stack is a safer bet than a better-known brand that depends on one relationship it does not control. Then ask who owns compliance and whether they are in the room when products are scoped, because the answer predicts both the risk and the rework.
What are the most important fintech and payments technologies professionals should understand?
The ledger first, because everything else is an opinion about it: double entry, idempotency, and reconciliation against what the bank says happened. Then the rails and their timing and finality properties, card network messaging, risk and fraud tooling, identity verification, and the APIs that let other companies embed your product. Underneath all of it, the durable technical skill is designing for partial failure, because networks time out after money has moved.
How do payment networks, processors, gateways, and digital wallets work together?
A gateway takes the transaction from the merchant. A processor handles the messaging and the settlement mechanics. The network routes the authorisation between the acquiring side and the issuing bank, and sets the scheme rules and fees. The issuer approves or declines and ultimately carries the customer relationship. A digital wallet sits in front of all of it, usually tokenising the card rather than replacing the chain. Each party takes a cut and each holds some form of veto, which is why the economics and the dependencies matter as much as the technology.
How are AI and automation changing fintech jobs, required skills, and career opportunities?
AI has landed hardest on the control functions and on support, where volume, pattern recognition and documentation are the whole job: fraud and financial crime detection, onboarding checks, dispute handling and first-line support have all changed materially, and the review queues that consumed most of a financial crime department are smaller than they were. What has not changed is accountability, since a regulator will ask who decided and on what basis. The roles genuinely shrinking are the manual review ones, not the ones deciding what the machine may do.
What regulations and compliance requirements should fintech and payments professionals understand?
Enough to know which regime your product sits in and what it forbids. For most roles that means money transmission and licensing, anti-money-laundering and sanctions obligations, consumer protection and fair treatment rules, data protection, and the card scheme rules, which are not law but function like it. The practical standard is not legal expertise, it is knowing when a design decision has crossed into something that needs a specialist, and asking before rather than after it ships.
Senior-Level
How are real-time payments, stablecoins, and embedded finance changing the payments industry?
All three attack the same thing, which is the cost and friction of moving value. Instant rails remove float and change dispute economics, because instant and final are the same property seen from two sides, which is a genuine problem for fraud controls that assumed reversibility. Stablecoins matter most where existing rails are slow or expensive, particularly cross-border. Embedded finance moves distribution into non-financial products, pushing value toward infrastructure at one end and the brand that owns the customer at the other, and compressing the undifferentiated middle.
What career paths lead from fintech analyst or specialist to product manager, director, or executive?
By becoming the person who can hold the commercial case and the regulatory constraint in the same sentence, which is rarer than it sounds. The reliable path is to take an unglamorous ownership that nobody wants, a rail migration, a licence application, a remediation programme, and finish it. Financial managers, where much of this leadership is counted, sit at a median of $166,570 with five years or more of related experience listed as typical entry.
How do fintech professionals transition into specialized roles in payments, risk, fraud prevention, or compliance?
Move sideways inside your current employer, because these functions hire far more readily from people who already understand the product than from outside. Risk and fraud take numerate people from operations and analytics. Compliance takes people who can write clearly and read a rule carefully, and values an anti-money-laundering certification. Payments takes anyone who has demonstrated they understand settlement and reconciliation. In every case, asking to sit in on the function's meetings for a quarter is the cheapest way to find out whether you want it.
How do fintech companies balance innovation, cybersecurity, fraud prevention, and regulatory compliance?
By building the control functions in rather than bolting them on. Licensing determines what the product may be at all, so it belongs in the first design conversation, not the final review. Fraud is a dial rather than a target of zero, because the last basis point usually costs more in rejected good customers than it saves. The pattern that fails is a product built to a deadline and shown to compliance at the end, because the rework is total and because a control function that only ever says no will be routed around.
How do senior fintech and payments professionals evaluate emerging technologies and new business models?
Ask what regulatory perimeter it sits in and who bears the loss when it fails, before asking what it enables. Most new models in this sector are a rearrangement of who holds the licence, who holds the risk and who owns the customer, and the ones that work are usually the ones where that rearrangement is honest about all three. Then look at unit economics at scale rather than at launch, because thin margins mean a model that works at a thousand transactions can be unviable at a million.
How should fintech leaders build teams, develop partnerships, and scale payment products and platforms?
Hire for the pairing rather than the pedigree: people from banks who can move at product speed, and people from technology who take regulation seriously. Put the control functions in the same room as the product teams from the start. On partnerships, treat the sponsor bank and the processor as strategic rather than procurement, know your concentration, and have a plan for losing one, because that is the risk that ends companies and it moves faster than any enforcement action.
How should fintech executives prepare their organizations for AI, regulatory changes, and the future of digital payments?
Start from what the organisation is allowed to be, then from what it can earn. A strategy that holds up names its regulatory perimeter explicitly, states which partner relationships it depends on, and carries a plan for losing one. On AI, the binding constraint is explainability and accountability rather than capability, so invest in model governance alongside the models. On rails, assume instant and embedded distribution keep growing, and position at either the infrastructure end or the customer-owning end rather than in the middle.
Get Tomorrow's Fintech Professional Briefing
The enforcement action that changes what your sponsor bank will allow was published this morning.