CRE Investor Career Guide
Explore commercial real estate investing jobs, salaries, and career paths. Stay current on property values, interest rates, and CRE market trends.
Top CRE Investment News, in 5 Minutes
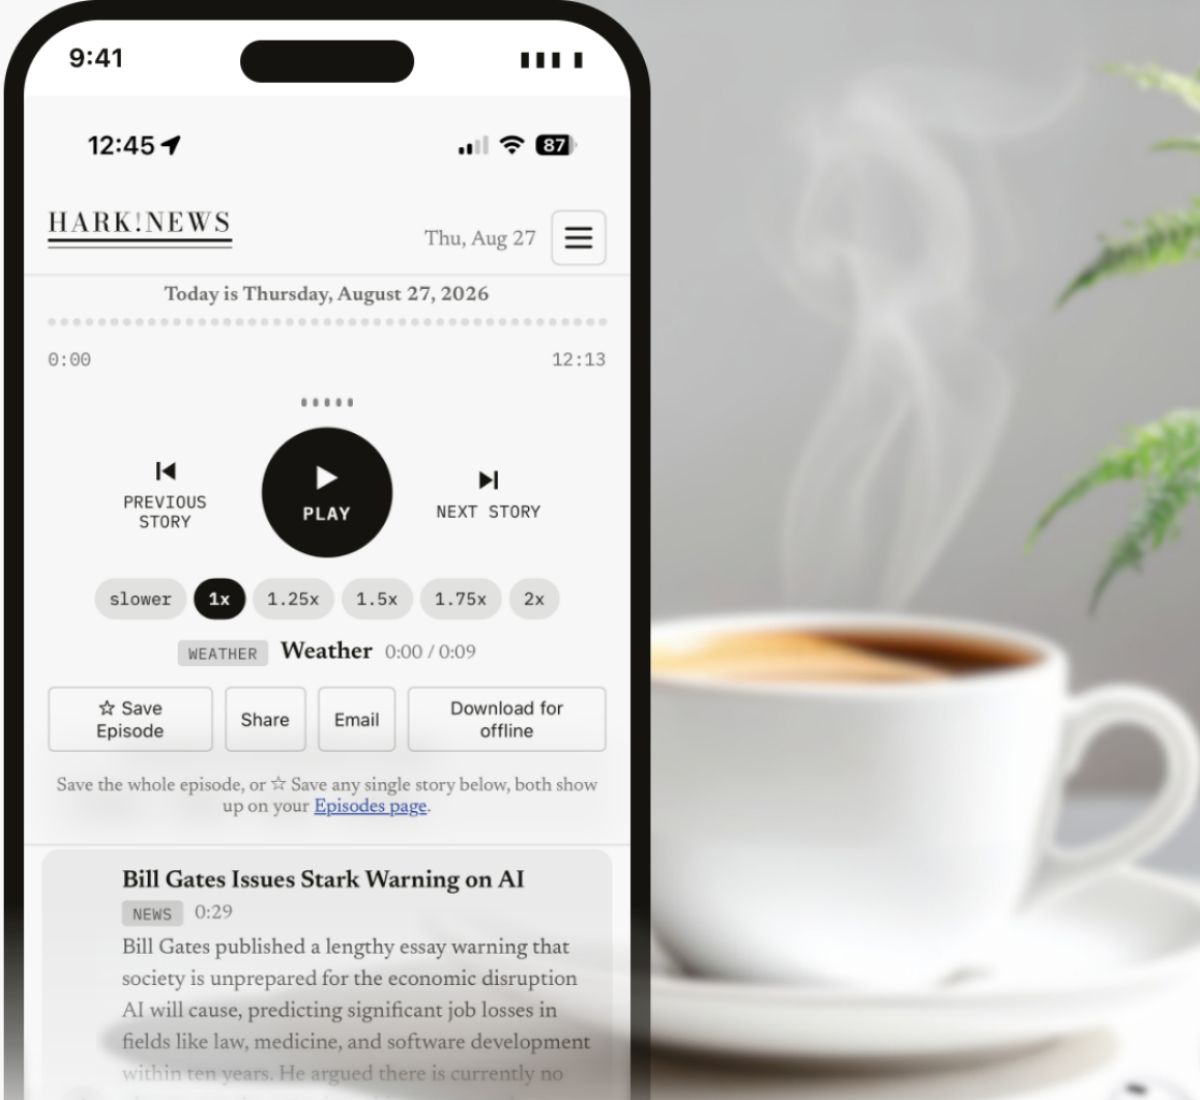
We handpick the best commercial real estate investing newsletters and distill the latest news and insights into a 5-minute audio briefing, texted to you every morning.
Try the CRE Investor Briefing, FreeFreeSee the 6 newsletters we handpicked
At a glance
CRE Investing at a Glance
There is no federal occupation called commercial real estate investor, so the wage picture has to be assembled: financial analysts at a $103,570 median in May 2025, financial managers at $166,570, and property, real estate and community association managers at $69,990 for the operating side. Those miss the part that defines senior pay, which is carried interest, a share of profits that arrives years after the work and only if the deals performed. Careers run analyst, associate, vice president, principal, and the hard transition is from pricing deals to sourcing them. Nearly every permanent loss in this business traces back to leverage and to an exit assumption nobody stress-tested.
Key Industry Statistics
$103,570
Median pay for financial analysts (May 2025)US Bureau of Labor Statistics
$166,570
Median pay for financial managers (May 2025)US Bureau of Labor Statistics
443,100
Financial analyst jobs in the USUS Bureau of Labor Statistics
+7%
Projected analyst growth, 2025 to 2035US Bureau of Labor Statistics
Common roles
- Acquisitions analyst
- Asset management analyst
- Associate
- Vice president
- Portfolio manager
- Principal
Where they work
- Real estate private equity funds
- REITs
- Developers
- Family offices
- Insurance and pension capital
- Debt funds
What decides pay
- Carried interest participation
- Fund size and strategy
- Sourcing or execution
- Asset class
- Track record you can evidence
Key Areas in CRE Investing
Acquisitions
Sourcing, underwriting and pricing the assets a strategy is built from.
Asset Management
Owning the business plan after closing and making the projection true.
Capital Markets
Arranging the debt whose terms decide the equity return.
Portfolio Strategy
Which sectors and markets to hold, and when to rotate out of them.
Development
Creating assets rather than buying them, at the highest risk on the ladder.
Investor Relations
Raising the capital and reporting honestly when plans slip.
Commercial Real Estate Investor Jobs & Salary
No federal occupation covers CRE investing directly, so this ladder uses the roles the work is actually counted under. All figures are median annual wages for May 2025, and they exclude carried interest, which is where senior compensation in this industry is concentrated.
Property, real estate, and community association managers
$69,990
Financial analysts
$103,570
Financial managers
$166,570
Real estate brokers
$73,220
Source: US Bureau of Labor Statistics, Financial Analysts, May 2025, accessed October 2026.
CRE Investing Career Paths
Four routes into the same decision: what an asset is worth and what to pay for it. The first fork is whether you buy assets or run them, and the second, much later, is whether you deploy capital or raise it.
- Acquisitions Analyst0 to 3 yearsUnderwriting deals other people sourced, and learning which assumptions quietly carry the return.
- Associate3 to 5 yearsRunning transactions through diligence and closing, with your own name on the recommendation.
- Vice President5 to 9 yearsSourcing rather than pricing. The transition that decides whether this becomes a career.
- Principal9 years and upStrategy, committee and carry, with returns attributable to deals you chose.
Credential that fits No licence required; modelling ability assumed
There is no federal occupation code for an acquisitions analyst, an asset manager or a real estate principal. Underwriting roles are counted among financial analysts, investment leadership among financial managers, and the operating side among property, real estate and community association managers. None of those figures include carried interest.
A Typical Day in CRE Investing Jobs
Five roles from the first model to the capital raise, ordered by how much of the day is somebody else's decision.
Acquisitions AnalystEntry-Level · Investment FirmModelling deals you did not source, and quietly learning which assumptions the firm actually argues about.
- 08:00Rebuilding a broker's model from the rent roll, because their expense line is always optimistic and sometimes creative.
- 10:30Comparable sales for a submarket you had not heard of last week, and a view on which trades are genuinely comparable.
- 13:00Debt sizing: coverage, loan-to-value and what a lender would actually do this month rather than last quarter.
- 15:00Investment committee memo, where your sensitivity table decides how the room talks about the deal.
- 18:00A second pass on the exit cap rate, which is the assumption the deal lives or dies on.
Asset Management AnalystEntry-Level · OwnerWatching projections meet buildings, which is the education acquisitions analysts do not get.
- 08:30Monthly variance: where operating expenses ran over budget and whether the property manager has an explanation.
- 10:00Lease abstract for a renewal, checking the option terms somebody agreed to four years ago.
- 12:30Capital project tracking, because the roof replacement in the business plan is now two quarters late.
- 14:30Rebuilding the hold model with actual performance, which rarely flatters the original underwriting.
- 16:30Quarterly investor reporting pack, where the honest version of a slipped plan has to be written down.
AssociateMid-Level · AcquisitionsRunning live transactions through diligence while sourcing enough to prove you can.
- 07:30Diligence call: the environmental report flagged something and the timeline now has a decision in it.
- 09:30Broker catch-ups, which are the slow construction of being shown deals before they are marketed.
- 11:30Repricing a live deal after the lender moved, and deciding whether to retrade or walk.
- 14:00Site visit, because a model cannot tell you the loading dock will not take a modern trailer.
- 17:00Screening three new opportunities, two of which die in twenty minutes and should.
Vice PresidentSenior · Investment FirmSourcing, which is the part of the job no model prepares you for.
- 08:00Owner call about an asset with debt maturing next year, a conversation scheduled around their problem.
- 10:00Investment committee, defending a deal where you are the only person who has walked the building.
- 12:30Lunch with a lender, because financing relationships decide which deals you can credibly bid on.
- 15:00Reviewing an associate's model and finding the growth assumption doing all the work.
- 17:30Pipeline: the four off-market situations you are nursing, none of which will transact this quarter.
Portfolio ManagerSenior · FundAllocation and capital, where the question is which market rather than which building.
- 08:00Portfolio review: concentration by sector, market and lender, and where the next maturity wall sits.
- 10:00Limited partner call about a fund underperforming its projection, with no good version of the answer.
- 12:00Hold or sell on an asset that has met its business plan early, which is a harder call than it sounds.
- 14:30Strategy for the next vintage, including the sectors you were wrong to avoid last time.
- 16:30Fundraising materials, where every claim about track record has to survive diligence.
JOB SEARCH
How to Become a Commercial Real Estate Investor in 2026
Whether you are chasing a first analyst seat, making the jump from pricing deals to sourcing them, or raising capital against your own track record, the questions change at each stage. Pick yours.
Entry-Level
Break Into CRE Investing
How to get a first underwriting seat, what the analytical screen is really testing, and why the unglamorous side of the business teaches more.
What you should know about the field
What the job pays and how it is actually counted.
No federal occupation describes this job
CRE investing is not a BLS category, so the wage picture is assembled from financial analysts at $103,570, financial managers at $166,570 and property managers at $69,990, all May 2025 medians.
Source: US Bureau of Labor Statistics, Financial Analysts, May 2025
The analyst seat is counted as financial analysis
Underwriting roles sit inside financial analysts, median $103,570 across 443,100 jobs growing 7 percent to 2035, which is the fair comparison when weighing an offer against banking or corporate finance.
Source: US Bureau of Labor Statistics, Financial Analysts, May 2025
Acquisitions and asset management are different jobs
One decides what to buy, the other makes the projection true afterwards. Asset management is treated as the lesser seat and routinely produces the better buyers.
Source: US Bureau of Labor Statistics, Property, Real Estate, and Community Association Managers, May 2025
Strategy labels are a risk ladder
Core, core-plus, value-add and opportunistic describe how much of the return comes from the market and how much from the business plan, and how much leverage sits underneath it.
Source: US Bureau of Labor Statistics, Property, Real Estate, and Community Association Managers, May 2025
Skills employers look for
What a first investing seat is screened on.
Building a model rather than filling one in
An acquisition model from a blank sheet: rent roll, expenses, debt, hold period and exit, with every assumption traceable to evidence you can name.
Source: US Bureau of Labor Statistics, Financial Analysts, May 2025
Reading a rent roll with suspicion
Lease expiries, concessions buried in the terms, tenants paying above market who will not renew there, and the difference between the seller's operating expenses and real ones.
Source: US Bureau of Labor Statistics, Property, Real Estate, and Community Association Managers, May 2025
Understanding the capital stack
Loan-to-value, debt service coverage, fixed against floating, interest-only periods, recourse, and the maturity date, which is the line item that actually decides outcomes.
Source: US Bureau of Labor Statistics, Financial Managers, May 2025
Submarket supply judgement
Counting what is under construction and what it will do to absorption, because oversupply is local, knowable in advance, and has sunk more business plans than any recession.
Source: US Bureau of Labor Statistics, Property, Real Estate, and Community Association Managers, May 2025
Interview questions and answers
Expect a modelling test and a reason to defend it.
Underwrite this acquisition and tell me what you would pay.
What they are looking for: Whether you can model from first principles under time pressure. Nearly every investing interview includes a version of this.
I would build in-place net operating income from the rent roll less real operating expenses, layer debt sized to a coverage ratio the lender would actually accept, hold for five years with leasing assumptions I can defend from comparable deals, and solve for the price that clears the firm's return hurdle rather than starting from the asking price.
Make it yours: Solve for price rather than validating the guide price. Candidates who reverse-engineer a yes are the ones who get declined.
Explain the difference between IRR and cash-on-cash to a new investor.
What they are looking for: Whether you understand what the metrics actually measure, not just how to compute them.
Cash-on-cash is what you receive each year against the equity you put in, so it tells you about income. IRR is the annualised return across the whole hold including the sale, so it rewards speed and weights the exit heavily. A deal can look strong on one and weak on the other, and knowing which matters depends on whether the investor needs income or a return of capital.
Make it yours: Say where they diverge. Reciting definitions reads as memorised; the divergence shows you have used them.
Why asset management rather than acquisitions, or the other way round?
What they are looking for: Self-knowledge, and whether you understand what each seat actually involves day to day.
Acquisitions, because I want to own the pricing decision, but I would take an asset management seat first if it were offered. Watching what happens to a projection after closing is the fastest way to learn which assumptions were honest, and I would rather learn that on someone else's deal than my own.
Make it yours: Show you know the unglamorous seat has value. Dismissing asset management is a common and visible tell.
How would higher rates change what you pay for this building?
What they are looking for: Whether you understand repricing mechanically rather than as commentary.
Two ways. Debt costs more, so the same income supports less leverage and less price. And required returns rise, so the exit cap rate widens, which hits the back end hardest because the sale is the biggest single cash flow. The income can be entirely unchanged and the value still falls materially.
Make it yours: Separate the two channels. Candidates who mention only the cost of debt have half the picture.
Mid-Level
From Pricing to Sourcing
Running transactions through diligence, forming views you defend in committee, and making the transition that decides whether this becomes a career.
What you should know about the field
What moves returns once you own the decision.
Leverage causes nearly every permanent loss
Debt magnifies both directions. The losses that end careers are refinancing into a weak market and an exit cap rate that was optimistic when it was typed, not operating mistakes.
Source: US Bureau of Labor Statistics, Financial Managers, May 2025
Rates reprice assets whose income never changed
Higher debt costs cut what a buyer can pay and lift required returns, pushing cap rates up. A fully let building can lose a fifth of its value without a single tenant leaving.
Source: US Bureau of Labor Statistics, Financial Analysts, May 2025
The hard transition is from pricing to sourcing
Analyst and associate work is execution. Vice president means bringing deals, which is a network rather than a skill, and it is where most investment careers stall.
Source: US Bureau of Labor Statistics, Financial Managers, May 2025
Carried interest is the part that is missing
Senior compensation is salary, bonus and a share of profits that pays years after the work and only if the deals performed. Published medians cannot see it, which is why they understate the top of this career badly.
Source: US Bureau of Labor Statistics, Financial Managers, May 2025
Skills employers look for
What separates execution from judgement.
Defending an exit assumption
The exit usually drives the return more than anything else and gets examined least. Being able to say what the exit cap rate rests on separates analysts from associates.
Source: US Bureau of Labor Statistics, Financial Analysts, May 2025
Saying no with a reason
Articulating what would have to be true for a deal to work and whether you believe it, instead of tuning a growth assumption until the return clears the hurdle.
Source: US Bureau of Labor Statistics, Financial Analysts, May 2025
Executing a business plan after closing
Leasing strategy, capital projects, expense control and refinancing. The purchase was a hypothesis; this is the part that proves or disproves it.
Source: US Bureau of Labor Statistics, Property, Real Estate, and Community Association Managers, May 2025
Understanding the capital stack
Loan-to-value, debt service coverage, fixed against floating, interest-only periods, recourse, and the maturity date, which is the line item that actually decides outcomes.
Source: US Bureau of Labor Statistics, Financial Managers, May 2025
Interview questions and answers
Questions that test opinion rather than technique.
What would have to be true for this deal to work?
What they are looking for: Calibrated scepticism, which is the single trait that distinguishes good underwriters.
Rents would need to grow faster than the submarket has managed in any of the last five years, and the exit would need a cap rate tighter than today's. Either is possible, both together is a bet on the market rather than on the asset, and I would want to be paid for that rather than assume it.
Make it yours: Name the specific assumption and say whether you believe it. A general answer about risk is not an answer.
Walk me through a deal you turned down.
What they are looking for: Judgement and the confidence to have an opinion. The best answer in this interview is usually a rejection.
A value-add multifamily asset where the plan depended on renovating units to rents only two comparable buildings had achieved, both newer. The yield on cost looked fine, but it needed every unit to turn on schedule and no new supply nearby, and there were four hundred units under construction a mile away.
Make it yours: Use a real deal and give the number that killed it. Vague caution is indistinguishable from inexperience.
What do you think is mispriced in this market right now?
What they are looking for: Market engagement and the nerve to commit to a view in front of people who will disagree.
I think well-located older office in secondary markets is being priced as though every building in the sector is impaired, when the capital expenditure needed to make some of them competitive is knowable and sometimes modest. It is unpopular, which is usually where the mispricing is.
Make it yours: Have one view and hold it under pushback. The interviewer will argue; that is the test.
Tell me about a model of yours that turned out to be wrong.
What they are looking for: Honesty and whether you learned something structural rather than blaming the market.
I underwrote lease-up over nine months on an industrial asset and it took sixteen. My error was using the submarket's average absorption rather than looking at the specific competing space that was available, which was a quarter of the market in two buildings with better clear heights.
Make it yours: Name the methodological mistake, not the external event. An answer that blames rates learns nothing.
Senior
Deploy or Raise Capital
Owning strategy and attribution, deciding which markets to hold rather than which building to buy, and eventually raising the capital yourself.
What you should know about the field
What seniority is actually paid for.
Carried interest is the part that is missing
Senior compensation is salary, bonus and a share of profits that pays years after the work and only if the deals performed. Published medians cannot see it, which is why they understate the top of this career badly.
Source: US Bureau of Labor Statistics, Financial Managers, May 2025
The hard transition is from pricing to sourcing
Analyst and associate work is execution. Vice president means bringing deals, which is a network rather than a skill, and it is where most investment careers stall.
Source: US Bureau of Labor Statistics, Financial Managers, May 2025
Leverage causes nearly every permanent loss
Debt magnifies both directions. The losses that end careers are refinancing into a weak market and an exit cap rate that was optimistic when it was typed, not operating mistakes.
Source: US Bureau of Labor Statistics, Financial Managers, May 2025
Strategy labels are a risk ladder
Core, core-plus, value-add and opportunistic describe how much of the return comes from the market and how much from the business plan, and how much leverage sits underneath it.
Source: US Bureau of Labor Statistics, Property, Real Estate, and Community Association Managers, May 2025
Skills employers look for
What is expected of someone deploying other people's capital.
Saying no with a reason
Articulating what would have to be true for a deal to work and whether you believe it, instead of tuning a growth assumption until the return clears the hurdle.
Source: US Bureau of Labor Statistics, Financial Analysts, May 2025
Reporting honestly when the plan slips
Telling investors early that a projection has moved. The capital you raise next depends far more on this than on the deals that went well.
Source: US Bureau of Labor Statistics, Financial Managers, May 2025
Defending an exit assumption
The exit usually drives the return more than anything else and gets examined least. Being able to say what the exit cap rate rests on separates analysts from associates.
Source: US Bureau of Labor Statistics, Financial Analysts, May 2025
Executing a business plan after closing
Leasing strategy, capital projects, expense control and refinancing. The purchase was a hypothesis; this is the part that proves or disproves it.
Source: US Bureau of Labor Statistics, Property, Real Estate, and Community Association Managers, May 2025
Interview questions and answers
Questions for someone expected to bring deals and capital.
How do you source deals that are not already on the market?
What they are looking for: Whether you understand the transition every investing career has to make eventually.
Pick a sector and a few submarkets, build a list of owners by hold period and debt maturity, and work it steadily. Maturities are public and they create motivated sellers on a schedule. Brokers bring the marketed deals; the proprietary ones come from being the call an owner takes before they list.
Make it yours: Mention debt maturities. It is concrete, it is knowable, and most candidates never raise it.
How would you raise capital for your first deal independently?
What they are looking for: Realism about what capital actually follows, for anyone pitching at a senior level.
A single asset with a handful of backers who already know my work, structured so they see every number. Capital follows an attributable track record, not a title, so the first deal is really about creating something verifiable rather than about the returns on that one building.
Make it yours: Acknowledge that attribution is the constraint. Candidates who talk about fundraising before track record reveal they have not tried.
What do you think is mispriced in this market right now?
What they are looking for: Market engagement and the nerve to commit to a view in front of people who will disagree.
I think well-located older office in secondary markets is being priced as though every building in the sector is impaired, when the capital expenditure needed to make some of them competitive is knowable and sometimes modest. It is unpopular, which is usually where the mispricing is.
Make it yours: Have one view and hold it under pushback. The interviewer will argue; that is the test.
Walk me through a deal you turned down.
What they are looking for: Judgement and the confidence to have an opinion. The best answer in this interview is usually a rejection.
A value-add multifamily asset where the plan depended on renovating units to rents only two comparable buildings had achieved, both newer. The yield on cost looked fine, but it needed every unit to turn on schedule and no new supply nearby, and there were four hundred units under construction a mile away.
Make it yours: Use a real deal and give the number that killed it. Vague caution is indistinguishable from inexperience.
Why Commercial Real Estate Investors Need to Stay Informed
Changing property values, interest rates, cap rates, and AI-powered technology are reshaping commercial real estate investing. Staying current on market trends, financing, and investment opportunities helps investors evaluate deals, manage risk, and maximize returns.
Read more
The mechanical reason is that underwriting is built on comparables and on the cost of debt, and both move faster than a quarterly report. An investor working from stale evidence is not slightly behind, they are pricing a market that has already gone.
The bottom line
CRE Investment Markets Are Shifting. Stay Ahead.
Pay here is salary, bonus and carried interest, and only the first two are predictable. The durable asset is a track record attributable deal by deal, which is also the thing nobody can build for you in a hurry.
Stay Informed with Hark's CRE Investor Briefing
How it works
Curated from the best newsletters
Hark's editorial team handpicks the sources worth following. See how we rank
Distilled into one briefing
Six sources become a single five-minute read of what actually changed.
Texted to you every morning
It arrives before you open the model, at a time you choose.
Links back to the original
Every item names its source, so you can read the full piece when it matters.
The 6 CRE Investing Newsletters We Handpicked
CRE Daily
CRE Daily
- Free
- daily
- 65k readers
"5 minutes or less" morning brief on commercial real estate, 65k+ professional readers.
Why commercial real estate investors read it
The fastest daily read on transactions, capital markets and sector movement. Five minutes that tell you whether anything repriced overnight.
More about this newsletter
CRE Daily is a five-minute morning brief on commercial real estate, read by 65,000+ operators, developers, brokers, and investors. It compresses deals, data, and market shifts into a fast professional read. Free, with regional editions for Texas and New York.
Best for: Operators, developers, and brokers who want a five-minute daily read compressing commercial real estate deals, data, and market shifts.
Commercial Observer Daily National
Observer Media (Commercial Observer)
- Freemium
- Daily
Daily email from Commercial Observer rounding up the day's most important national commercial real estate stories.
Why commercial real estate investors read it
Deal-level national coverage with genuine depth on financing structures, which is the half of an acquisition that decides the equity return.
More about this newsletter
Daily National is one of 15+ CO newsletters, delivering a same-day roundup of top national CRE news from Commercial Observer's reporting staff; sibling editions cover New York, LA, South Florida, D.C., finance, proptech, and more. Commercial Observer is Observer Media's commercial real estate publication. Newsletter signup is free; full article access sits behind a paid CO membership.
See the other 4 newsletters
CoStar News
CoStar Group
- Freemium
- Daily
Commercial real estate news from CoStar Group's newsroom, with daily email alerts; full access is part of the CoStar platform, with some free bulletins.
Why commercial real estate investors read it
Coverage from the newsroom attached to the industry's valuation and comparables data, which is the evidence base underwriting actually rests on.
More about this newsletter
CoStar's newsroom covers CRE transactions, leasing, and market trends across the US, with daily news alerts tailored to your markets. Full CoStar News access rides on a paid CoStar subscription, though free news bulletins (e.g., the hotels newsletters) are open to non-subscribers.
GlobeSt
ALM Global
- Free
Email newsletters from GlobeSt.com, ALM's commercial real estate news brand, spanning national CRE news plus regional and sector editions like multifamily and net lease.
Why commercial real estate investors read it
National CRE news plus sector editions like multifamily and net lease, which map directly onto the asset classes an investment strategy is defined by.
More about this newsletter
GlobeSt's newsroom offers a flagship CRE news briefing plus regional (e.g., California/West) and sector deep-dives such as healthcare property, multifamily, net lease, and industrial. Subscribing requires a free ALM digital reader account; most articles are free with registration, some premium content is gated.
Multi-Housing News Daily (MHN Daily News Brief)
Multi-Housing News
- Free
- Daily
Daily headlines on the U.S. multifamily and apartment industry from the editorial team of trade publication Multi-Housing News.
Why commercial real estate investors read it
Multifamily transactions, financing and rent fundamentals, daily. The asset class most portfolios are long, covered at the resolution underwriting actually needs.
Listen to Multi-Housing News Daily (MHN Daily News Brief) free
More about this newsletter
The MHN Daily News Brief rounds up the day's multifamily headlines (deals, development, finance, and operations) plus interviews with industry leaders, economic updates, and market forecasts. Multi-Housing News has covered the apartment sector since 1966, in print until 2012 and online since. A separate breaking-news newsletter is available on the same signup form.
The Real Deal
The Real Deal
- Freemium
- Daily
The trade paper of real estate: breaking coverage of major deals, developers, and brokerages in NYC, LA, Miami, and beyond.
Why commercial real estate investors read it
Large transactions, developers and ownership changes across the major markets, which is usually where distress, forced sales and genuine opportunity become visible first.
More about this newsletter
The Real Deal is the trade paper of real estate, covering deals, developers, brokerages, and the personalities behind them across the major US markets. It is dense with names and numbers and reads like an insider's feed. Best for people who work in property or follow it closely.
Best for: Property professionals who want dense, name-and-numbers coverage of deals, developers, and brokerages across major US markets.
You May Also Like
- CRE BrokersThe agency side of every deal you price, paid in commission on closing rather than in carry years after the hold ends.
- Private EquitySame fund structure and the same carried interest, applied to operating companies instead of buildings, with diligence that looks at people rather than rent rolls.
- Property ManagementWhere the net operating income in your model is actually produced, and the discipline that decides whether a business plan lands on schedule.
- Investment BankingA comparable analytical start with steeper hours and faster pay, advising on transactions rather than carrying the risk in them.
Frequently Asked Questions
Entry-Level
What does a commercial real estate investor do?
Buys income-producing property to earn a return on capital, then manages it to the projection. In practice the role splits: acquisitions decides what to buy and at what price, underwriting the rent roll, expenses, financing and exit; asset management owns the asset afterwards, pushing rents, controlling costs and executing whatever business plan justified the purchase. Most people in the industry are investing other people's money and are measured on what that capital returns.
How do you become a commercial real estate investor?
Most careers start as an acquisitions or asset management analyst at a fund, REIT, developer or family office, where you underwrite deals for two to three years before you are trusted to source them. The alternative is investing your own capital in small assets, which teaches the same lessons more slowly and more expensively. The entry filter is almost entirely modelling ability plus a demonstrated understanding of how a property actually makes money.
What are the best entry-level jobs in commercial real estate investing?
Acquisitions analyst, which is the straightest line and the most competitive. Asset management analyst, which is underrated: you learn what happens to projections after the closing dinner, and that knowledge makes you a better buyer later. Valuation or appraisal, and brokerage research, both of which teach comparables and submarkets and feed people into investing roles every year. Debt roles at a lender teach the capital stack from the side that gets paid first.
Do you need a finance or real estate degree to work in commercial real estate investing?
No degree is legally required, but institutional hiring is concentrated in finance, real estate, economics and accounting programmes, and the analytical screen is real. People move in from brokerage, lending, appraisal, construction and accounting routinely. What substitutes for the degree is a model you can build from a rent roll and an operating statement without a template, and the ability to explain every assumption in it.
How much do commercial real estate investment professionals earn?
There is no federal occupation for this work, so the honest proxies are financial analysts at a $103,570 median in May 2025 and financial managers at $166,570, with property, real estate and community association managers at $69,990 covering the operating side. Those understate senior investment roles, because compensation here is salary plus bonus plus carried interest, and carry is the part that makes the career worth it and the part that pays years late or not at all.
What is the typical career path from acquisitions analyst to investment manager?
Analyst for two to three years underwriting what others source, then associate, where you run deals through diligence and start handling relationships. Vice president means sourcing: you are expected to bring deals, not just price them. Director and principal add capital raising and portfolio decisions. The transition that actually gates the career is from pricing deals to finding them, because the first is a skill and the second is a network.
What is the difference between a commercial real estate investor and a broker?
Which side of the table, and how you are paid. A broker is an agent: they are engaged to market an asset or represent a tenant, earn a commission when the transaction closes, and are right if the deal happens. An investor is a principal: they commit capital, carry the risk for years and are right only if the asset performs. A broker's bad deal costs them a reputation; an investor's bad deal costs them money, and they find out slowly.
Mid-Level
What is the difference between real estate acquisitions and asset management?
Acquisitions buys; asset management owns. Acquisitions is deal-driven, intense in bursts, and judged on what you declined as much as what you closed. Asset management is continuous: leasing strategy, capital projects, refinancing, operating expenses and the quarterly report to investors when reality diverges from the model. The industry treats acquisitions as the glamorous side, which is why asset managers often understand buildings better.
What skills do you need to succeed in commercial real estate investing?
Financial modelling that you can build rather than fill in. Enough grasp of leases, construction and operations to know which line items are real. Market judgement about supply, demand and absorption at submarket resolution. Then the one that separates careers: calibrated scepticism, being able to say what would have to be true for this deal to work and whether you believe it, instead of adjusting a growth assumption until the return clears the hurdle.
How do commercial real estate investors evaluate potential investments?
Start with the income: the rent roll, lease expiries, actual operating expenses rather than the seller's version, and what the net operating income really is today. Then the business plan, which is whatever you intend to do that the current owner is not. Then the capital stack and what debt costs. Then the exit, which is usually the single largest driver of return and the assumption examined least carefully. Then comparables, as a check rather than a conclusion.
What are NOI, cap rates, IRR, and cash-on-cash returns?
Net operating income is rental income less operating expenses, before debt and capital spending. The capitalisation rate is NOI divided by price, a yield that also prices risk: lower cap rates mean a safer or more sought-after asset. Internal rate of return is the annualised return across the whole hold including the sale, so it rewards speed as well as size. Cash-on-cash is annual cash after debt service divided by equity invested, which is what an investor actually receives each year.
How does commercial real estate financing work?
Most purchases combine equity with a mortgage secured on the property, sized by loan-to-value and by the debt service coverage ratio, the test of whether income comfortably covers payments. Larger deals add mezzanine debt or preferred equity between the two. The terms matter as much as the rate: fixed or floating, interest-only periods, recourse, and above all the maturity date, because a loan maturing into a bad market is how otherwise sound assets are lost.
How do interest rates affect commercial property values and investment returns?
Directly, through two channels. Higher rates raise the cost of debt, which cuts what a buyer can pay for the same income, and they lift the return investors demand, which pushes cap rates up and prices down. An asset whose income has not changed at all can lose a fifth of its value purely on repricing. Rates also decide refinancing: fixed-rate debt expiring into higher rates can turn a performing asset into a forced sale.
What is the difference between core, core-plus, value-add, and opportunistic real estate investing?
A risk and return ladder. Core is stabilised, well-let property in strong markets, low leverage, income-driven, lowest return. Core-plus is the same with a little more leasing risk or deferred maintenance. Value-add is where the business plan does the work: renovate, re-lease, reposition, with returns coming from the improvement rather than the market. Opportunistic is development, distress and repositioning at the highest leverage, where the upside is real and so is losing the equity.
Senior
What are the biggest risks in commercial real estate investing?
Leverage, which magnifies both directions and causes nearly every permanent loss. Interest rate and refinancing risk, especially a maturity landing in a weak market. Tenant concentration, where one departure wipes out a year's income. Oversupply, which is local and knowable in advance if you count the cranes. Illiquidity, because you cannot exit quickly at any sensible price. And the quiet one: an exit cap rate assumption that was optimistic when it was typed.
How do you prepare for a commercial real estate investment job interview?
Expect a modelling test and prepare to build rather than recall: a simple acquisition model with debt, a hold period and an exit, and be ready to defend every assumption. Know the firm's strategy, asset classes and recent deals. Bring a live deal you have underwritten yourself, even a small one, and have a view on it. Then be ready for the real question, which is what you would need to believe to buy it at the asking price.
What financial modeling, software, and data tools should CRE investment professionals learn?
Spreadsheet modelling first and with genuine fluency, because it remains the medium every investment decision is argued in. Then the market data and comparables platforms the industry prices against, a cash flow and valuation package for institutional work, and whatever portfolio and asset management system your firm reports from. Tools change; the durable skill is auditing somebody else's model fast enough to find the assumption it depends on.
How is AI changing commercial real estate investing?
Fastest at the screening and document layer: abstracting leases, pulling rent rolls into a model, assembling comparables and producing first-pass memoranda, which together are a large share of what analysts spent their hours on. Valuation tooling is improving at the quick indicative answer. What has not changed is who carries the risk. A model is a set of assumptions about the future, and a faster model is a faster set of assumptions, not a better one.
What is the difference between commercial real estate investing and real estate private equity?
Real estate private equity is a structure, not a separate activity. A fund raises discretionary capital from limited partners against a stated strategy, invests it over a defined period, and earns fees plus carried interest. Investing more broadly includes REITs, developers, family offices, insurers and individuals, who use their own balance sheets and face no fundraising clock. The investing work rhymes; the pressure differs, because a fund must deploy capital on a timetable.
Can you transition from commercial real estate brokerage into investing?
Regularly, and it is one of the better-worn paths. Brokers arrive with market knowledge, deal flow and owner relationships that a trained analyst does not have. What usually needs proving is underwriting depth, since advising on a price is not the same as defending one with your firm's capital. The adjustment people find hardest is not analytical but temperamental: income becomes a salary and a bonus, and being right takes years to confirm.
How can commercial real estate investment professionals advance into fund management or start their own investment firm?
Build a track record you can evidence deal by deal, because capital is raised against attribution rather than against a title. Senior roles add capital raising and investor relations to investing, and running a firm makes those the job. Going independent usually starts with a single asset and a handful of backers who know your work, then a programmatic joint venture, then a discretionary fund. The constraint is almost never finding deals; it is that nobody funds a track record they cannot verify.
Get Tomorrow's CRE Investing Briefing
Six sources, one briefing, five minutes a morning. Enough to know what repriced before you open the model.