Corporate Development Career Guide
Explore corporate development jobs, salaries, and career paths. Stay current on M&A deals, valuations, and industry trends.
Top M&A and Corporate Development News, in 5 Minutes
We handpick the best M&A and business newsletters and distill the latest deals, valuations, and news into a 5-minute audio briefing, texted to you every morning.
Try the Corporate Development Briefing, FreeFreeSee the 4 newsletters we handpicked
At a glance
Corporate Development at a Glance
Financial managers, the occupation most corporate development leaders are counted in, held about 879,700 jobs in 2025 and are projected to grow 10 percent through 2035. The work extends well beyond signing deals. It covers strategists who build the thesis and the target list, analysts who value businesses and model the combination, deal leads who run a process from first call to signing, diligence coordinators who pull finance, legal, tax, commercial and people into one view of the risk, and integration managers who own whether the thing you bought actually works. Pay tracks the rung rather than the title: analyst and associate roles sit near the financial and investment analyst median of $102,740, while directors and heads sit near the financial manager median of $166,570, which rises to $172,340 inside management of companies and enterprises, the industry that holds most corporate head offices. The strengths rewarded are not only quantitative, because somebody has to write the board paper, run a diligence workstream six functions trust, and tell a sponsoring executive their favourite target is priced wrong. Most people arrive from investment banking, consulting, transaction services or an operating finance seat. The direction of travel is heavier antitrust scrutiny on large transactions, where the 2026 US premerger filing threshold starts at $133.9 million, and more pressure to prove value after the close rather than at the announcement.
Key Industry Statistics
$166,570
Median pay for financial managers (May 2025)US Bureau of Labor Statistics
$102,740
Median pay for financial and investment analystsUS Bureau of Labor Statistics
879,700
Financial manager jobs in 2025US Bureau of Labor Statistics
$133.9M
Deal size triggering a 2026 US premerger filingUS Federal Trade Commission
Common roles
- Corporate development analyst
- Corporate development manager
- M&A integration manager
- Director of corporate development
- VP of corporate development
- Head of strategy and M&A
Where they work
- Public operating companies
- Private equity portfolio companies
- Software and technology groups
- Healthcare and pharma groups
- Industrial and energy groups
- Family offices and holding companies
What decides pay
- Deal volume and size
- Public or private employer
- Sector and deal complexity
- Integration accountability
- Board exposure
Key Areas in Corporate Development
Pipeline & Sourcing
Finding targets before a banker brings them to everyone at once.
Strategic Rationale
Why this asset, for us, instead of building the capability ourselves.
Valuation & Modelling
What a business is worth to this owner, not to the market.
Diligence Coordination
Pulling six functions into one honest view of the risk.
Board & Approval
The paper that asks a board to commit real money.
Integration & Value
Whether the synergies in the model ever reach the accounts.
Corporate Development Jobs & Salary
There is no federal occupation called corporate development, so this ladder uses the Bureau of Labor Statistics occupations the work is actually counted in, from the sell-side seat many people arrive from to the executive line a head of corporate development reports into. All figures are median annual wages for May 2025 and exclude the deal bonus, which carries much of the upside at the senior end.
Securities, commodities, and financial services sales agents
$78,660
Financial and investment analysts
$102,740
Financial managers
$166,570
Chief executives
$213,990
Source: US Bureau of Labor Statistics, Financial Managers, May 2025, accessed October 2026.
Corporate Development Career Paths
Four routes through one question: what should this company own that it does not own yet. The first fork is whether you run processes or set the thesis, and the later one is whether you follow the deal past the close.
- Corporate Development Analyst0 to 2 yearsThe model, the comparables and the appendix, learning what a process actually looks like.
- Manager, Corporate Development2 to 5 yearsOwning a workstream, then a small deal, including the timetable you do not control.
- Senior Manager, M&A5 to 8 yearsRunning a process end to end and negotiating the terms that follow a diligence finding.
- Director, M&A8 years and upSeveral deals at once, and the price discipline nobody else in the room is paid for.
Credential that fits No licence required; modelling fluency assumed
There is no SOC code for corporate development. The work is counted among financial and investment analysts early on and financial managers later, and neither median includes the deal bonus that makes up a meaningful share of senior pay.
A Typical Day in Corporate Development Jobs
Five roles from a first valuation to the capital allocation decision, ordered by how much of the day belongs to somebody else's timetable.
Corporate Development AnalystEntry-Level · ValuationOne model, one target, and the slow discovery of how little a spreadsheet settles.
- 08:30Updating the comparable transactions table after an overnight deal reset the multiple.
- 10:00Rebuilding the standalone case from the target's filings, because their plan is optimistic.
- 13:00Pulling the synergy assumptions apart with procurement, who have never seen them.
- 15:00Drafting the appendix pages nobody reads until the one meeting where they do.
- 17:00Reading the deal wires and flagging two targets that changed owner today.
Corporate Development ManagerMid-Level · Deal ExecutionRunning a live process, where the timetable belongs to a seller and six functions want different things.
- 08:00Diligence stand-up: tax has found an exposure and nobody can price it yet.
- 10:30Negotiating the data room scope with the seller's adviser, politely and twice.
- 12:30Reworking the model after commercial diligence halved a revenue synergy line.
- 14:30Counsel on whether the deal is reportable, and what that does to the timetable.
- 16:30Telling the sponsoring executive the price has moved, before anybody else does.
M&A Integration ManagerMid-Level · Post-Merger IntegrationOwning the half of the deal that decides whether any of the model was true.
- 08:30Day one readiness review, where payroll and email access are the actual risks.
- 10:00Chasing a synergy line that has an owner on paper and nobody in practice.
- 12:00Retention conversations with three people the thesis quietly depends on.
- 14:30Systems sequencing, because finance wants one ledger and the business wants peace.
- 16:30Writing the honest monthly update, including the line that has slipped again.
Director of Corporate DevelopmentSenior-Level · PipelineA target list tied to strategy, and the conversations that start a year before a process does.
- 08:00Pipeline review: ranking targets by the owner's reason to sell, not by fit.
- 10:00Coffee with a founder who is not selling, which is the point of the meeting.
- 12:00Pushing back on a business unit's favourite target, with the comparables to show why.
- 14:00Board paper draft, cutting it down to the two assumptions that drive the answer.
- 16:30Post-close review of last year's acquisition against the paper that approved it.
VP of Corporate DevelopmentSenior-Level · LeadershipCapital allocation, the board relationship, and the deals the company decides not to do.
- 08:00Chief financial officer session on whether this year's capital belongs in M&A at all.
- 10:00Antitrust counsel on a transaction large enough to attract a serious review.
- 12:00Declining an approach, which takes longer than accepting one and matters more.
- 14:00Portfolio review, including the business the company no longer owns best.
- 16:30Grading the last three acquisitions in public, which sets the bar for the next.
JOB SEARCH
How to Get Into Corporate Development in 2026
Whether you are moving across from banking, consulting or an operating finance seat, running your first process end to end, or deciding how much of next year's plan should rest on an acquisition at all, the questions change at each stage. Pick yours.
Entry-Level
Break Into the Deal Team
How to get in from banking, consulting or an internal finance seat, what the pay proxies really mean, and why a deal you can talk through beats a certificate.
What you should know about the field
What the job pays, who gets hired, and how it differs from advising.
No Federal Occupation Is Called Corporate Development
The work is counted among financial and investment analysts, a $102,740 median in May 2025, and financial managers, a $166,570 median. Every salary figure you read for this role is an adjacent proxy rather than the job itself.
Sources: US Bureau of Labor Statistics, Financial and Investment Analysts, May 2025US Bureau of Labor Statistics, Financial Managers, May 2025
Banking Is a Common Entry, Not a Requirement
Securities, commodities and financial services sales agents, the occupation investment bankers are counted in, earn a $78,660 median across about 531,000 jobs projected to grow 1 percent. The sell side is one door, not the door.
Consulting Is the Other Large Feeder Into These Teams
Management analysts held about 1,077,100 jobs in 2025 at a $101,860 median and are projected to grow 10 percent through 2035. Commercial diligence work puts them beside corporate development constantly.
Source: US Bureau of Labor Statistics, Management Analysts, May 2025
The CFA Is Optional and Expensive in Time
Three exams, around 300 hours of study each, and 4,000 hours of relevant experience completed over no fewer than 36 months for the charter. CFA Institute puts the whole program at three to four years.
Source: CFA Institute, CFA Program
Skills employers look for
What a team checks in someone who has not run a process yet.
Valuing a Business to This Buyer
Discounted cash flow and comparables are table stakes. The in-house version adds what the asset is worth with our distribution, our cost base and our customers attached, which is the number the board is actually approving.
Source: US Bureau of Labor Statistics, Financial and Investment Analysts, May 2025
Running Diligence Across Functions
Finance, legal, tax, technology, commercial and people each find something. The skill is sequencing them and deciding which findings change the price, which change the contract, and which change nothing.
Source: US Bureau of Labor Statistics, Management Analysts, May 2025
Writing the Board Paper
A paper that states the rationale, the price, the downside and what has to be true, in language a non finance director can challenge. Most of this job's influence runs through that document.
Source: US Bureau of Labor Statistics, Financial Managers, May 2025
Reading the Antitrust Clock
Knowing early whether a deal is reportable, what the waiting period does to the timetable, and how that shapes the signing to closing gap you promise the operating business.
Source: US Federal Trade Commission, Premerger Notification Program
Interview questions and answers
Questions put to a candidate moving into their first in-house deal seat.
Walk me through how you would value an acquisition target.
What they are looking for: Whether you can separate the market's price from this company's price.
A discounted cash flow on the standalone plan, sanity checked against trading and transaction comparables. Then the part that matters here: a second case with our distribution, our procurement and our overlap removed, because that difference is the most we can justify paying and still earn a return.
Make it yours: Name the standalone and the combined case separately. Candidates who give one number are valuing it as an investor, not as an owner.
How do you decide between building, partnering and buying?
What they are looking for: Capital allocation judgement rather than deal enthusiasm.
By time, certainty and what we would still own afterwards. Building is cheapest and slowest and keeps everything. Partnering is fast and reversible and keeps nothing durable. Buying is expensive and immediate and comes with people and systems you now have to run. I would argue the case on which of those constraints actually binds us.
Make it yours: Say what you would still own in three years. It is the test most answers skip.
A business unit head wants to buy a company. What do you do first?
What they are looking for: Whether you start with the strategy or with the spreadsheet.
Ask what capability or position we are trying to get, and whether buying is the cheapest way to get it. Half the time the honest answer is a partnership or a hire. If buying is right, I would size the gap before touching a model, because the model will say yes to almost anything.
Make it yours: Lead with build, partner or buy. Opening a model first is the commonest weak answer.
How would you source targets that are not already in a process?
What they are looking for: Whether you can build a pipeline or only react to bankers.
Map the capability gaps first, then the companies that fill them, then the owners and their likely reason to sell: succession, a fund approaching the end of its life, a founder tired of raising. Then start conversations with no transaction attached, early enough that we are a phone call rather than a bid.
Make it yours: Name the seller's reason to sell. Target lists without owners are wish lists.
Mid-Level
Own a Process End to End
Running a deal whose timetable belongs to a seller, holding six functions to one view of the risk, and defending a price after diligence moves it.
What you should know about the field
What moves price, timetable and approval once the deal is yours.
Corporate Headquarters Is Its Own Pay Band
Inside management of companies and enterprises, the industry that holds most group head offices, financial managers earn a $172,340 median against $166,570 overall, and financial and investment analysts earn $101,760.
Sources: US Bureau of Labor Statistics, Financial Managers, May 2025US Bureau of Labor Statistics, Financial and Investment Analysts, May 2025
Large Deals Must Be Cleared Before They Close
Parties to reportable transactions notify the Federal Trade Commission and the Department of Justice, and may not close until the statutory waiting period has passed. The 2026 size of transaction threshold is $133.9 million.
Sources: US Federal Trade Commission, Premerger Notification ProgramUS Federal Trade Commission, Premerger Notification Program: Current Thresholds
The Market Is Large and Corporate Capital Is Cautious
Bain put global M&A at $4.9 trillion in 2025, a 40 percent rise and the second highest year on record, while the share of company capital allocated to acquisitions fell to a 30 year low.
Source: Bain & Company, Global M&A Report 2026 (press release)
The Occupation Above You Is Still Growing
Financial managers held about 879,700 jobs in 2025 and are projected to grow 10 percent through 2035. The handbook names developing financial plans for mergers and acquisitions among treasurers' and finance officers' duties.
Source: US Bureau of Labor Statistics, Financial Managers, May 2025
Skills employers look for
What separates running a workstream from owning a transaction.
Writing the Board Paper
A paper that states the rationale, the price, the downside and what has to be true, in language a non finance director can challenge. Most of this job's influence runs through that document.
Source: US Bureau of Labor Statistics, Financial Managers, May 2025
Running Diligence Across Functions
Finance, legal, tax, technology, commercial and people each find something. The skill is sequencing them and deciding which findings change the price, which change the contract, and which change nothing.
Source: US Bureau of Labor Statistics, Management Analysts, May 2025
Reading the Antitrust Clock
Knowing early whether a deal is reportable, what the waiting period does to the timetable, and how that shapes the signing to closing gap you promise the operating business.
Source: US Federal Trade Commission, Premerger Notification Program
Pricing the Risk You Found
The handbook notes an increased emphasis on risk management in finance. In a deal that means converting a diligence finding into an indemnity, an escrow, a lower price or a walk away.
Source: US Bureau of Labor Statistics, Financial Managers, May 2025
Interview questions and answers
Questions that test judgement under a real constraint.
A business unit head wants to buy a company. What do you do first?
What they are looking for: Whether you start with the strategy or with the spreadsheet.
Ask what capability or position we are trying to get, and whether buying is the cheapest way to get it. Half the time the honest answer is a partnership or a hire. If buying is right, I would size the gap before touching a model, because the model will say yes to almost anything.
Make it yours: Lead with build, partner or buy. Opening a model first is the commonest weak answer.
What would make you walk away from a deal in diligence?
What they are looking for: Whether you have a real threshold or only a process.
Something that breaks the thesis rather than the price. Customer concentration we cannot see past, revenue that turns out to be the founder's relationships, or a culture that makes the retention plan fiction. A tax exposure or a litigation tail is a price and indemnity conversation. A broken thesis is not.
Make it yours: Distinguish repriceable findings from thesis-breaking ones. That line is the whole answer.
How would you run diligence across functions on a tight timetable?
What they are looking for: Coordination instinct, which is most of the job and rarely rehearsed.
Start by writing down what each workstream is allowed to conclude, so nobody returns a general report. Front load the two findings that could kill the deal and sequence everything else behind them. Then hold one weekly session where functions hear each other, because the expensive issues sit between two workstreams.
Make it yours: Mention the cross-function session. Most answers describe parallel silos and call it coordination.
What goes in the board paper, and what gets left out?
What they are looking for: Whether you can write for people who will challenge you.
The rationale in one paragraph, the price and how it was reached, the downside case, the integration commitment and what has to be true for the returns to land. What gets left out is the model's detail and the enthusiasm. I would rather spend the space on the two assumptions that drive the answer.
Make it yours: Say what you cut. Papers that include everything hide the thing the board should argue about.
Senior-Level
Own the Pipeline and the Result
Deciding what the company should buy, what it should decline, and whether the last three acquisitions earned what their approval papers promised.
What you should know about the field
What seniority is actually accountable for in an in-house deal team.
The Market Is Large and Corporate Capital Is Cautious
Bain put global M&A at $4.9 trillion in 2025, a 40 percent rise and the second highest year on record, while the share of company capital allocated to acquisitions fell to a 30 year low.
Source: Bain & Company, Global M&A Report 2026 (press release)
The Line Above You Is a Small Occupation
Chief executives held about 291,600 jobs in 2025 at a $213,990 median and are projected to grow 3 percent through 2035. A head of corporate development usually reports into that line, through a finance or strategy chief.
Source: US Bureau of Labor Statistics, Top Executives, May 2025
Large Deals Must Be Cleared Before They Close
Parties to reportable transactions notify the Federal Trade Commission and the Department of Justice, and may not close until the statutory waiting period has passed. The 2026 size of transaction threshold is $133.9 million.
Sources: US Federal Trade Commission, Premerger Notification ProgramUS Federal Trade Commission, Premerger Notification Program: Current Thresholds
The Trade Body Is Older Than Most Deal Teams
The Association for Corporate Growth, founded in 1954, reports more than 14,000 members across 61 local markets and runs a Corporate Development Officers network, which is where in-house buyers meet each other.
Skills employers look for
What is expected of someone who sets the price discipline others work to.
Owning the Integration Plan
Naming who runs the acquired business on day one, which systems merge and when, and what the synergy number actually requires somebody to do. Deals disappoint here, not at signing.
Source: Bain & Company, Global M&A Report 2026 (press release)
Grading the Deal After the Close
Comparing the synergy case to the accounts a year on. Bain found four in five M&A executives expect to sustain or increase activity, which makes an honest scorecard on the last deal more valuable, not less.
Source: Bain & Company, Global M&A Report 2026 (press release)
Telling a Sponsoring Executive No
Saying the price does not work to the person whose idea the target was. Bain's own guidance is to test whether a deal helps the company compete or build capability faster, which means some do not.
Source: Bain & Company, Global M&A Report 2026 (press release)
Sourcing Before a Banker Calls
Keeping a live target list, knowing who owns what, and having had the first conversation a year before a process starts. Proprietary deals are won on relationships, not on process.
Interview questions and answers
Questions for someone expected to hold an independent view on capital.
How do you know whether our last acquisition worked?
What they are looking for: Whether you follow the money past the announcement.
Go back to the approval paper, take the synergy and growth case it promised, and find those lines in the accounts. Then separate what the acquired business did on its own from what the combination produced, because they get conflated constantly. If the answer is uncomfortable, that is the useful version.
Make it yours: Reference the original board paper. It shows you expect to be held to the number.
What goes in the board paper, and what gets left out?
What they are looking for: Whether you can write for people who will challenge you.
The rationale in one paragraph, the price and how it was reached, the downside case, the integration commitment and what has to be true for the returns to land. What gets left out is the model's detail and the enthusiasm. I would rather spend the space on the two assumptions that drive the answer.
Make it yours: Say what you cut. Papers that include everything hide the thing the board should argue about.
What would make you walk away from a deal in diligence?
What they are looking for: Whether you have a real threshold or only a process.
Something that breaks the thesis rather than the price. Customer concentration we cannot see past, revenue that turns out to be the founder's relationships, or a culture that makes the retention plan fiction. A tax exposure or a litigation tail is a price and indemnity conversation. A broken thesis is not.
Make it yours: Distinguish repriceable findings from thesis-breaking ones. That line is the whole answer.
How do you decide between building, partnering and buying?
What they are looking for: Capital allocation judgement rather than deal enthusiasm.
By time, certainty and what we would still own afterwards. Building is cheapest and slowest and keeps everything. Partnering is fast and reversible and keeps nothing durable. Buying is expensive and immediate and comes with people and systems you now have to run. I would argue the case on which of those constraints actually binds us.
Make it yours: Say what you would still own in three years. It is the test most answers skip.
Why Corporate Development Professionals Need to Stay Informed
Mergers, acquisitions, valuations, and competitive dynamics are constantly changing. Staying current on deal activity, market trends, and corporate strategy helps corporate development professionals identify opportunities, evaluate acquisitions, and make informed decisions.
Read more
The mechanical reason is pipeline. A target that raises a round, changes hands or trades at a new multiple changes both your list and your price, and almost none of that reaches you through your own deal flow before it is in the deal press.
The bottom line
Deal Markets Move Fast. Stay Ahead.
Anyone can build the model that justifies an acquisition. The people trusted with the next one are the ones who went back to the accounts afterwards, found out what the last deal really earned, and let that answer change the price they were willing to pay.
Stay Informed with Hark's Corporate Development Briefing
How it works
Curated from the best newsletters
Hark's editorial team handpicks the sources worth following. See how we rank
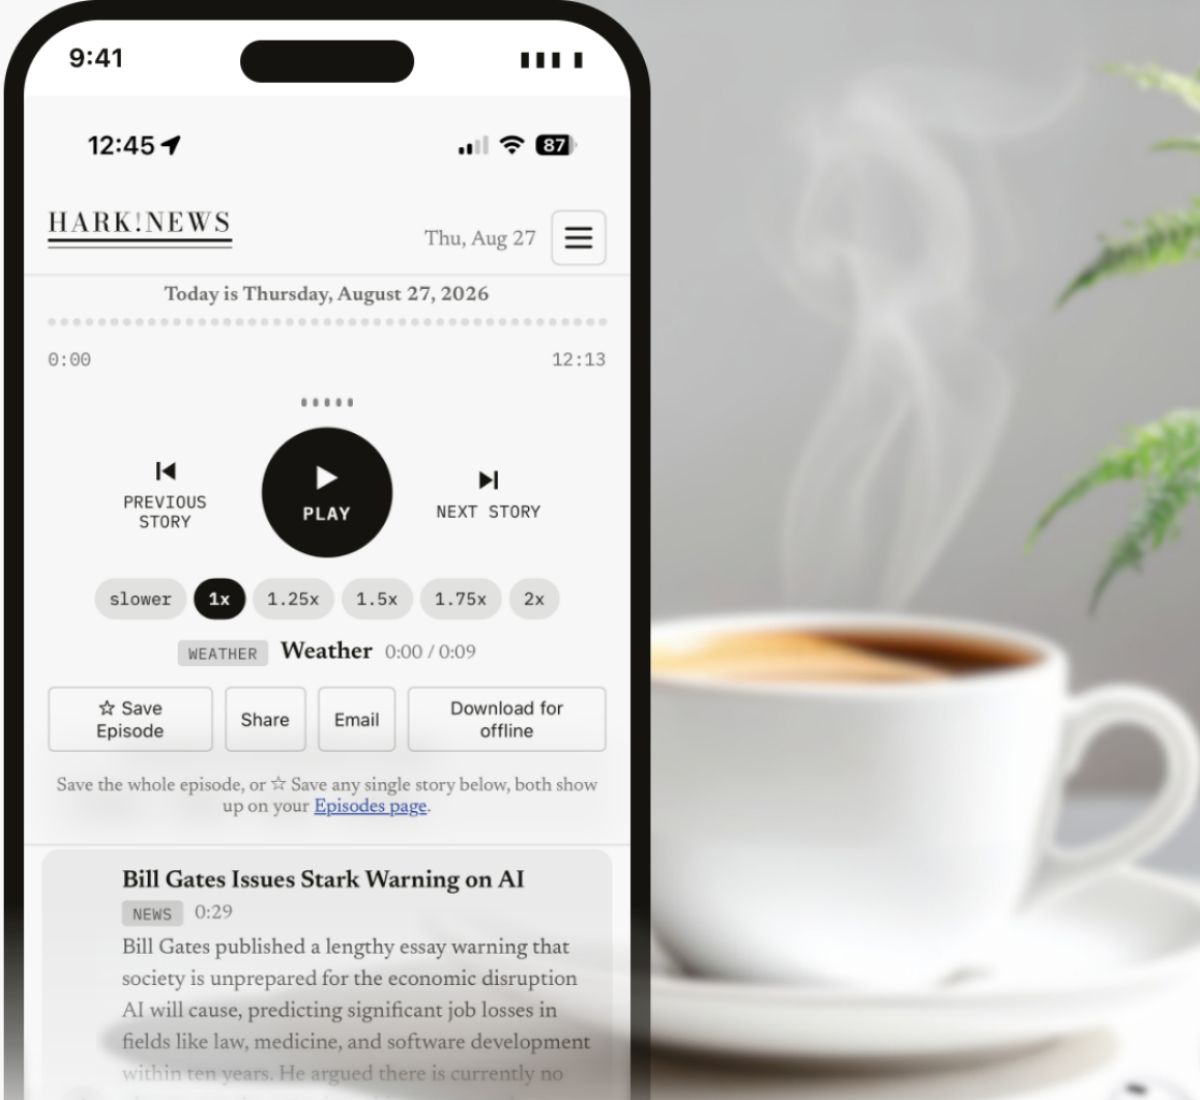
Distilled into one briefing
Four sources become a single five-minute read of what actually changed.
Texted to you every morning
It arrives before your first pipeline call, at a time you choose.
Links back to the original
Every item names its source, so you can read the full piece when it matters.
The 4 Corporate Development Newsletters We Handpicked
Axios Pro Rata
Axios (Dan Primack)
- Free
- Daily (weekdays)
Dan Primack's daily on venture capital, private equity, and the deals reshaping business.
Why corporate development professionals read it
Dan Primack's weekday wire on who is buying what, and the fastest way to learn that a company on your target list has just taken money from somebody else.
More about this newsletter
Dan Primack's Pro Rata is the morning must-read of the deals world: venture, private equity, and M&A scoops with the context to judge them, in Axios's ruthless brevity. When something big is about to happen in private markets, it tends to show up here first.
Best for: Private-markets professionals who want VC, PE, and M&A scoops with context, often before anyone else has them.
Term Sheet
Allie Garfinkle / Fortune
- Free
- Daily (weekdays)
Fortune's daily wire on VC, private equity, and M&A: the deals and the dealmakers behind them.
Why corporate development professionals read it
Fortune's daily read on private equity, venture and M&A, useful here because it names the funds and strategics bidding against you for the assets you want.
More about this newsletter
Fortune's weekday dealmaking newsletter, written by senior reporter Allie Garfinkle, covering venture capital, private equity, and M&A along with the people cutting the checks. It has been a fixture of the deals beat for over a decade under a rotating cast of Fortune finance writers, and now has a podcast companion.
Best for: Dealmakers who want a daily rundown of venture capital, private equity, and M&A from a reporter embedded with the people cutting the checks.
See the other 2 newsletters
The Daily Pitch (PitchBook)
PitchBook (a Morningstar company)
- Free
- Daily
- 1.5M readers
PitchBook's free daily email covering venture capital, private equity, and M&A news, paired with data and research from the PitchBook platform.
Why corporate development professionals read it
PitchBook's daily note on private market activity, where the comparable transactions and valuation marks behind a board paper usually surface first.
More about this newsletter
A daily briefing from PitchBook's news team that mixes VC, PE, and M&A headlines with proprietary deal data, league tables, and chart-driven analysis. PitchBook states more than 1.5 million industry professionals receive it. Related editions (Weekend Pitch, Daily Benchmark) can be added from the same subscribe page.
Best for: VCs, bankers, and founders raising money who want an institutional, data-backed daily digest of venture, private equity, and M&A news, like a free Bloomberg terminal briefing.
Finimize Daily
Finimize
- Free
- Daily (weekdays)
- 1M readers
Two market stories a day explained for people who don't trade for a living.
Why corporate development professionals read it
Two market stories a day in plain language, which keeps the macro backdrop to your cost of capital and your board's appetite for risk from going stale.
More about this newsletter
Finimize distills the day's two or three most important finance stories into plain English with a clear so-what for your money, in under five minutes. Built by analysts for people who refuse to choose between busy and informed.
Best for: Time-pressed readers who want the day's two or three most important finance stories with a clear so-what for their own money.
You May Also Like
- Investment BankersAdvisers on the other side of your table, running the sell-side process you are bidding into, and paid when a deal closes rather than on what it goes on to earn.
- Private Equity ProfessionalsFinancial buyers competing for the same assets, working to a fund's return clock and a hold period instead of a strategic rationale and a permanent balance sheet.
- Corporate Finance ProfessionalsThe planning and treasury colleagues who absorb your acquisition into the forecast and the capital structure once the announcement is over, and who own the synergy line afterwards.
- Management ConsultantsPartners on commercial diligence and integration planning, often the people who built the market view your board paper leans on, and a well travelled route into this career.
Frequently Asked Questions
Entry-Level
What does a corporate development professional do?
Buys companies on behalf of an operating business. Day to day that means keeping a target list tied to the company's strategy, valuing a business as it would be worth to this owner rather than to the market, running diligence across finance, legal, tax, commercial and people, writing the paper that asks a board to commit the money, and then staying with the deal through integration. The distinguishing duty is being accountable long after the advisers have left.
How do you get into corporate development?
Most people arrive from investment banking, strategy consulting, transaction services inside an accounting firm, or an internal finance or strategy seat at the company itself. Banking is the best known route and not the only one: securities and financial services sales agents, where bankers are counted, is a slow growing occupation, and teams increasingly hire from the business they are buying for. The thing that persuades is a deal you can walk through, including what you got wrong.
Is corporate development a good career?
The case for it is unusual: real influence over how a company spends its capital, exposure to the board early, and hours that are materially better than the sell side. The case against is that you do fewer deals, your bonus is rarely tied to deal volume, and a quiet year is genuinely quiet. It suits people who want to own an outcome rather than a transaction, and frustrates people who measure themselves in closings.
What is the difference between corporate development and corporate strategy?
Strategy decides where the company should be and corporate development is one of the instruments for getting there. In practice the two overlap and often sit in the same team: strategy frames the gap, corporate development tests whether buying is cheaper than building or partnering, and then executes if it is. The clean distinction is that strategy owns the question and corporate development owns the transaction and, increasingly, the result.
What is the difference between corporate development and investment banking?
Who you work for and when you stop. A banker is an adviser paid a fee when a transaction closes, usually on the sell side, running many processes at once. Corporate development is the principal: one balance sheet, one strategy, fewer deals, and no fee. The largest practical difference is that you cannot hand the company over at closing, because integration and the eventual verdict on the deal are yours.
Do you need an MBA to work in corporate development?
No. It is common, particularly at large companies and for people switching in from outside finance, but it is not a requirement and plenty of senior corporate development leaders do not have one. The Bureau of Labor Statistics puts a bachelor's degree as the typical entry education for both financial analysts and financial managers, with financial managers typically needing five years or more of related experience. Deal experience outranks the degree.
What are the best entry-level corporate development jobs?
An investment banking analyst seat, which teaches modelling and process faster than anything else. Transaction services or valuation at an accounting firm, which teaches diligence from the inside. A strategy analyst role at a company with an active acquisition programme, which is the most direct route. And a financial planning and analysis seat in a business unit, which is underrated: understanding how the company actually makes money is what makes a synergy case credible.
How much do corporate development professionals earn?
There is no federal occupation for corporate development, so the honest proxies are adjacent. Financial and investment analysts had a $102,740 median in May 2025, with the top ten percent above $180,860. Financial managers, where directors and heads are generally counted, had a $166,570 median, rising to $172,340 inside management of companies and enterprises, the industry that holds most corporate head offices. None of those medians include the deal bonus that lifts senior pay.
Mid-Level
What skills are most important for corporate development careers?
Valuation that distinguishes what a business is worth standalone from what it is worth to us, because that gap is the deal. Writing, because the board paper is where the decision is really made. Coordination, since diligence is six functions finding things that only matter in combination. Commercial judgement about build, partner or buy. And the willingness to tell a sponsoring executive that their target is priced wrong.
What is the typical corporate development career path?
Analyst, manager, senior manager, director, then vice president or head of corporate development, with a fork between staying a deal person and taking on strategy or integration leadership. Heads of corporate development typically report to a chief financial officer or chief strategy officer, and chief executives, the occupation above that line, had a $213,990 median in May 2025. Lateral moves into the operating business are common and usually help.
How do you transition from investment banking to corporate development?
Target the companies in sectors you have covered, because your value is knowing their landscape already. Rewrite your experience around judgement rather than throughput: what the deal was for, what you would have paid, what you would have walked away from. Expect the interview to probe whether you can live without a fee event, and prepare an honest answer about integration, which is the part bankers have never owned.
Can you enter corporate development without investment banking experience?
Yes, and it is more common than the job boards suggest. Transaction services, valuation practices, strategy consulting, internal strategy and financial planning teams all feed in, and management analysts, where consultants are counted, is a large and fast growing occupation that sits beside deal teams constantly. The gap to close is process fluency: knowing how a transaction runs from first call to signing, which you can learn on a live deal internally.
What financial modeling skills do corporate development professionals need?
A three statement model you can build from filings, a discounted cash flow, trading and transaction comparables, and accretion and dilution on the combined entity. Then the specific ones: purchase price allocation and how goodwill behaves, synergy modelling that separates cost from revenue and discounts the second heavily, and sensitivity work that shows the board which two assumptions the answer actually depends on.
How do corporate development teams identify acquisition targets?
By starting from the capability or market gap rather than from the available inventory. The sequence is to map the gap, map the companies that close it, then map the owners and their likely reason to sell: succession, a fund approaching the end of its hold period, a founder tired of fundraising. Bankers bring the rest, but anything that arrives in a competitive process is priced accordingly.
What role does due diligence play in corporate development?
It is where the price gets tested and where most deals are repriced or abandoned. Corporate development rarely does the work and always owns the sequencing: deciding what each workstream is allowed to conclude, front loading the findings that could kill the deal, and forcing functions to hear each other, because the expensive problems sit between two workstreams. The output is not a report, it is a revised price and a set of contract protections.
How do corporate development professionals value acquisition targets?
With two cases, not one. A standalone discounted cash flow sanity checked against trading and transaction comparables gives the market's view. Then a combined case with our distribution, procurement and overlap applied, which is what the asset is worth to this owner specifically. The difference is the synergy value, and the discipline is refusing to pay all of it away, because the premium is certain and the synergies are not.
Senior-Level
What is the difference between corporate development and private equity?
The clock and the exit. A fund buys to sell, usually inside a defined hold period, and the return is measured on that exit. A strategic buyer has a permanent balance sheet, no obligation to sell, and a rationale that depends on the acquired business fitting the one it already owns. That lets a strategic pay more for the right asset and makes it answerable for something a fund never is: whether the combination works.
How do you prepare for a corporate development interview?
Know the company's recent acquisitions, including the ones that went badly, and have a view on what you would do next and what you would not. Be ready to argue build, partner or buy on a real gap in their business. Expect a valuation walk-through and a question about walking away. Then prepare an honest view of where you think acquirers overpay, because the ability to say no is part of what is being tested.
What are common corporate development interview questions?
Walk me through how you would value this target. A business unit head wants to buy a company, what do you do first. How do you choose between building, partnering and buying. What would make you walk away in diligence. How would you run diligence across six functions on a tight timetable. How do you know whether our last acquisition worked. Most of them are testing capital allocation judgement rather than mechanics.
What is the work-life balance like in corporate development?
Better than banking on average and spikier than most corporate roles. Between live deals the job is pipeline work, strategy and integration reviews on a normal week. Inside a signing or a closing, the hours look like a bank's, including weekends, and the timetable is often set by an antitrust waiting period or a seller's process rather than by you. People who move across from the sell side describe it as the same peaks arriving far less often.
How do corporate development teams manage post-merger integration?
Badly, when it starts at closing. The teams that do it well write the integration plan during diligence, name an owner who is not the deal lead, and tie each synergy line to a person and a date rather than to a spreadsheet row. The structural problem is that the deal team is rewarded for signing and the business absorbs the consequences, which is why more companies now keep corporate development accountable for the first year of results.
What are the highest-paying corporate development roles?
Head or vice president of corporate development at a large public acquirer, particularly in technology, pharmaceuticals and financial services, where deals are frequent and large. The published proxy is financial managers, a $166,570 median in May 2025 rising to $172,340 inside management of companies and enterprises, with the top ten percent above $323,270; chief executives, the line above, had a $213,990 median. The variable is the deal bonus, which no federal figure captures and which separates two people on the same base.
How is AI changing corporate development and M&A?
Fastest at the document end. Reading a data room, pulling change of control clauses from hundreds of contracts, normalising a target's accounts and assembling a first comparables table were analyst weeks and are becoming supervised hours. Screening is changing too, because a target list is a filtering problem over market data. What has not moved is the part carrying the risk: a model will not tell you the revenue is the founder's relationships, and it will not write the board paper, because that is an argument made by somebody who will be held to it.
How do you advance to VP or Head of Corporate Development?
Not by closing more deals. The step up is from running transactions to allocating capital, which means owning the pipeline rather than the process, holding the board relationship directly, and being the person who says no to a sponsoring executive. The Bureau of Labor Statistics puts financial managers as typically needing five years or more of related experience, and the line above is chief executives, 291,600 jobs at a $213,990 median. The evidence that gets you there is a grade on your own closed deals.
Get Tomorrow's Corporate Development Briefing
Four sources, one briefing, five minutes a morning. Enough to walk into a pipeline review already knowing which of your targets moved overnight.